No first offer. The claim settled at the $190,000 dwelling limit.
The loss
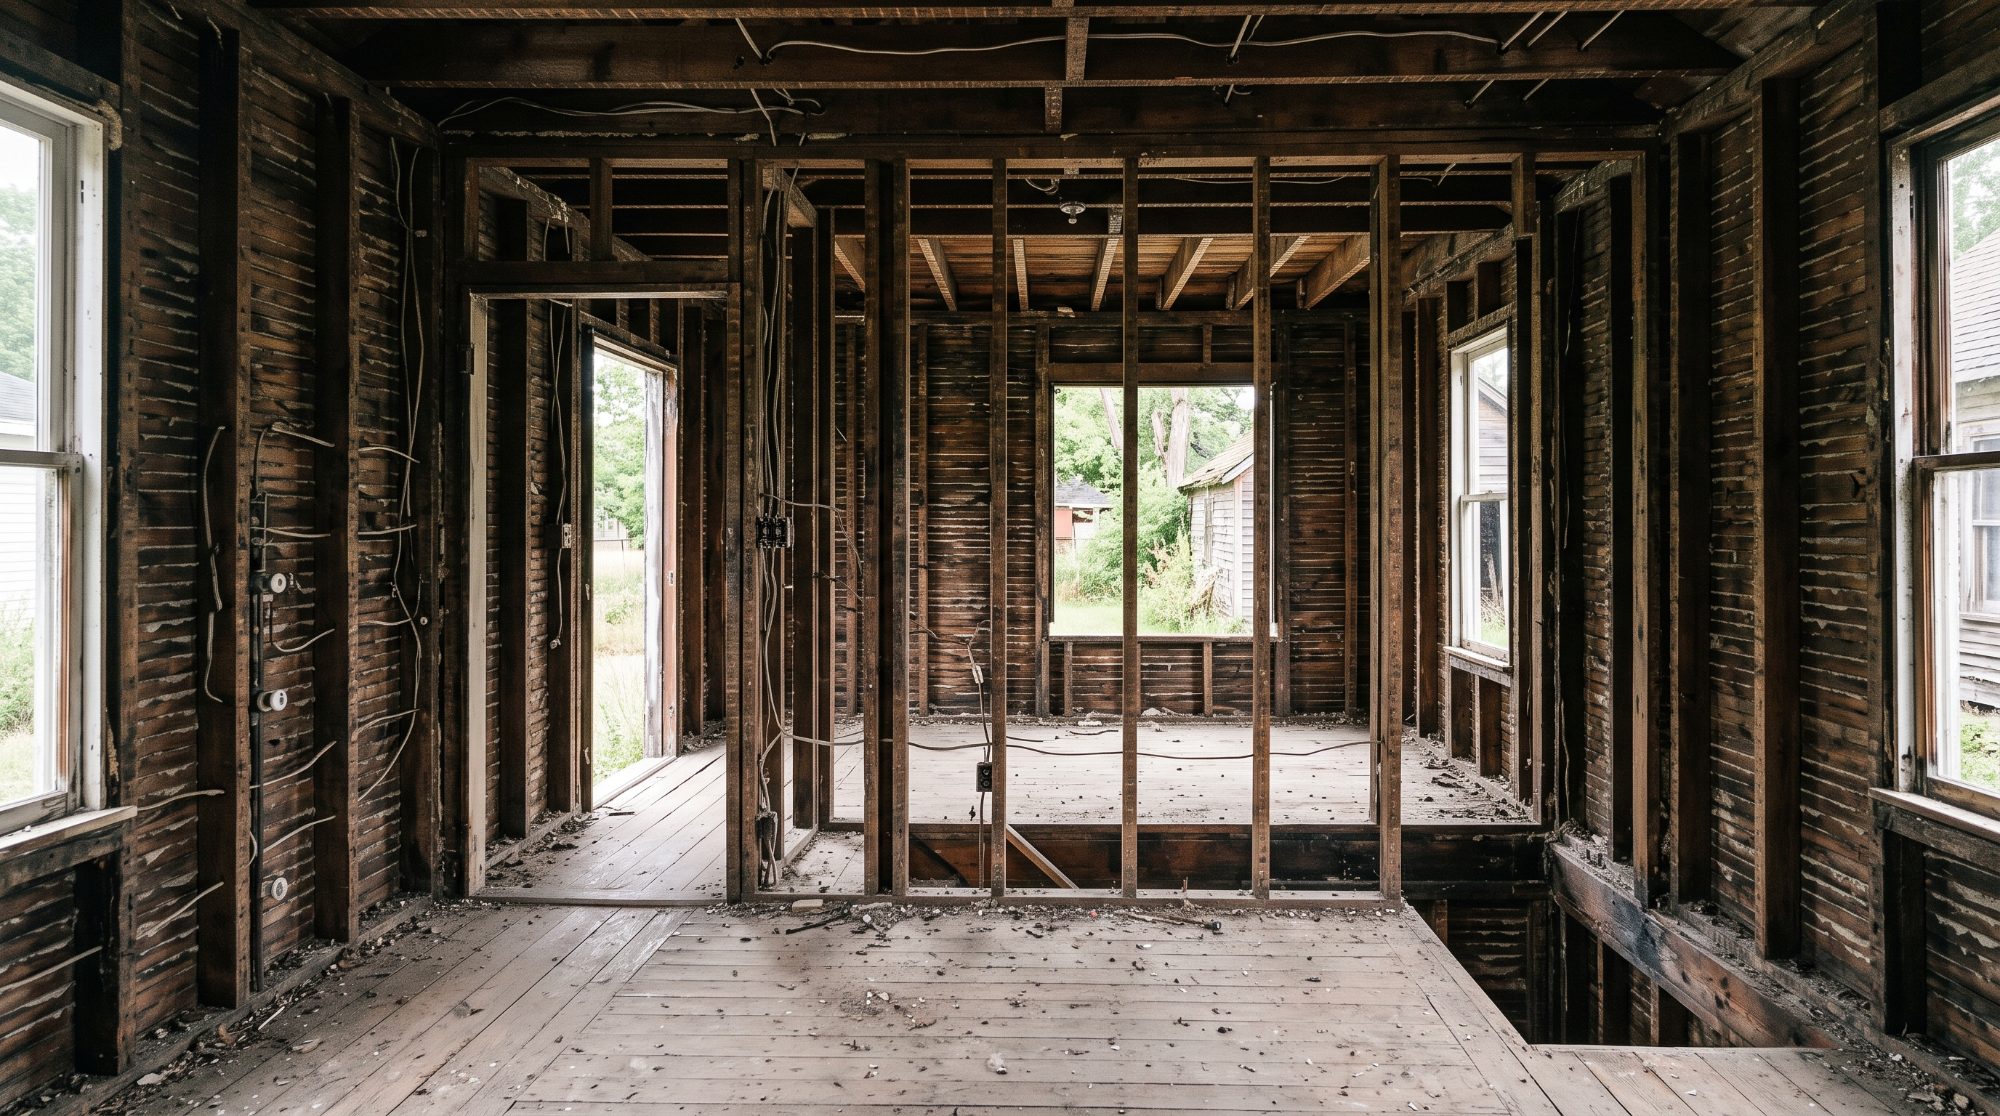
Fire tore through the upper floor of a Detroit home. The roof was open to the sky, the walls were charred through, and the structure had to be documented before anything was cleared away.
There was no offer on the table. We were engaged before the insurance company had put a number on the claim at all.
The first pass
- An offer is made first.
- The scope is argued backwards from it.
- Whatever is missing has to be proven.
- Some of it never comes back.
The full claim
- Documented before any number existed.
- Interior measured, roof and exterior measured.
- Every item for replacement photographed.
- Settled at the $190,000 dwelling limit.
What we did
We measured the interior with DocuSketch and the roof and exterior with EagleView, so the structure was on record from both sides before any scope was written.
What remained was a disagreement about which items had to be replaced rather than repaired. We answered it with photographs, item by item, until there was nothing left to dispute.
The outcome
The claim settled at the dwelling policy limit, about six and a half months after we were engaged. A limit is the most a policy can pay. Reaching it means the loss was documented all the way up to what the coverage allowed.
Identifying details are limited to protect client privacy. Figures are the insurance company's documented position and the final settlement on that claim. Every claim is different, and past results don't predict the outcome of any future claim.
Related
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.