A water claim is only as big as what
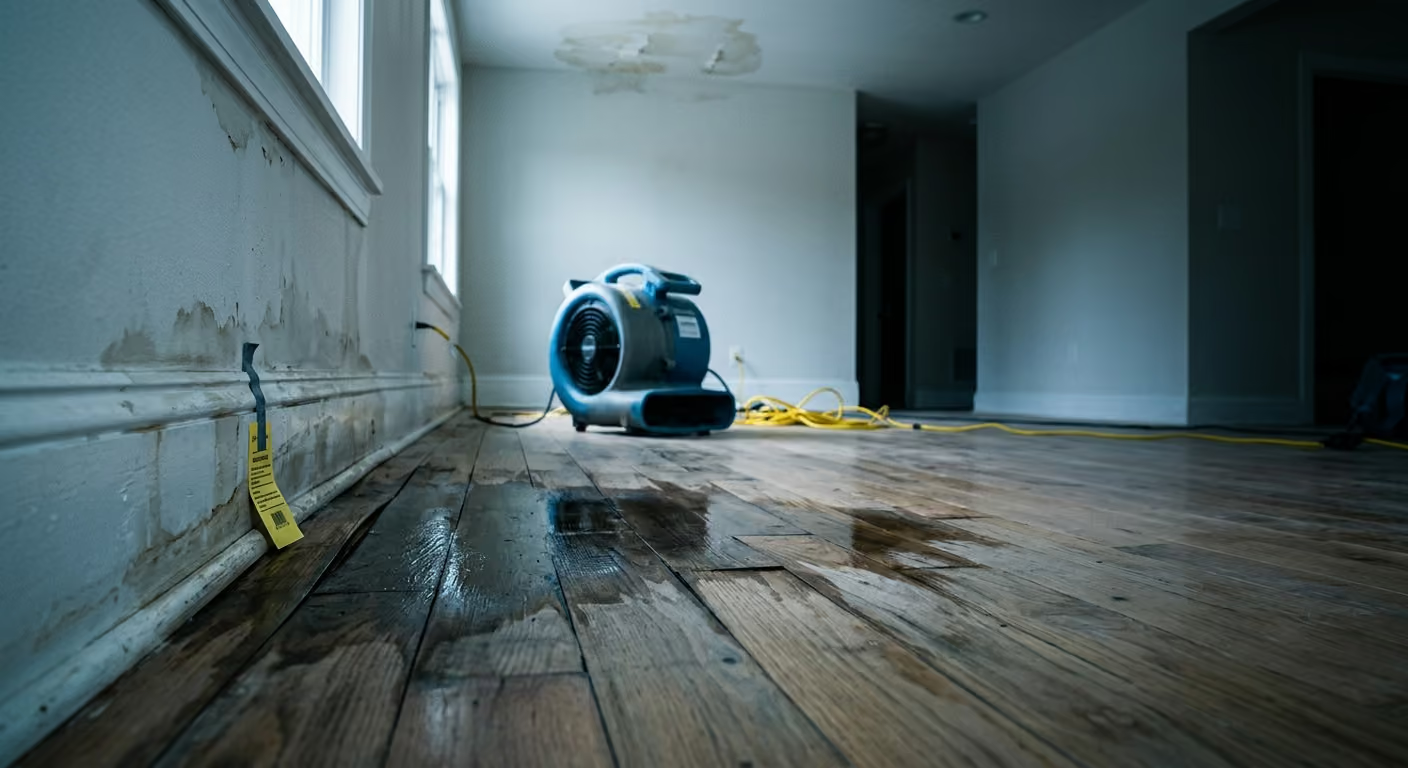
Water does most of its damage out of sight, and the evidence of it leaves in a dumpster within days. What your claim is worth is decided less by how bad it was than by how much of it was documented before the drying crew finished. This is where the proof usually goes missing.
The same loss,
Most people say they had a flood. Most people didn’t.
A flood is rising water from outside. It is excluded from nearly every homeowners policy and covered only by separate flood insurance. The water that ruined most houses came from somewhere else entirely: a supply line, a water heater, a toilet, or the unit upstairs. That difference is worth more than almost anything else on your claim.
Nobody saying flood is trying to mislead anyone. They are describing what it looked like to walk in. But the first description of a loss is the one that follows the file, long after everyone has forgotten who said it.
The two losses we handle most: a pipe that let go and sent water down through the house, and sewage that came up into it.
Six ways a water claim gets smaller than it should be
Read these against the estimate you have been handed.
Where the sewage came from
Backup of sewer and drain often carries a far lower limit. A failure inside your own drain system is not the municipal line backing up, and the plumber's report usually decides which one the file says it was.
Drying done to standard
ANSI/IICRC S500 sets how much material comes out, how long equipment runs and what gets recorded. Work done to an insurance company's preference instead leaves a dried building rather than a documented loss.
Moisture nobody opened a wall to find
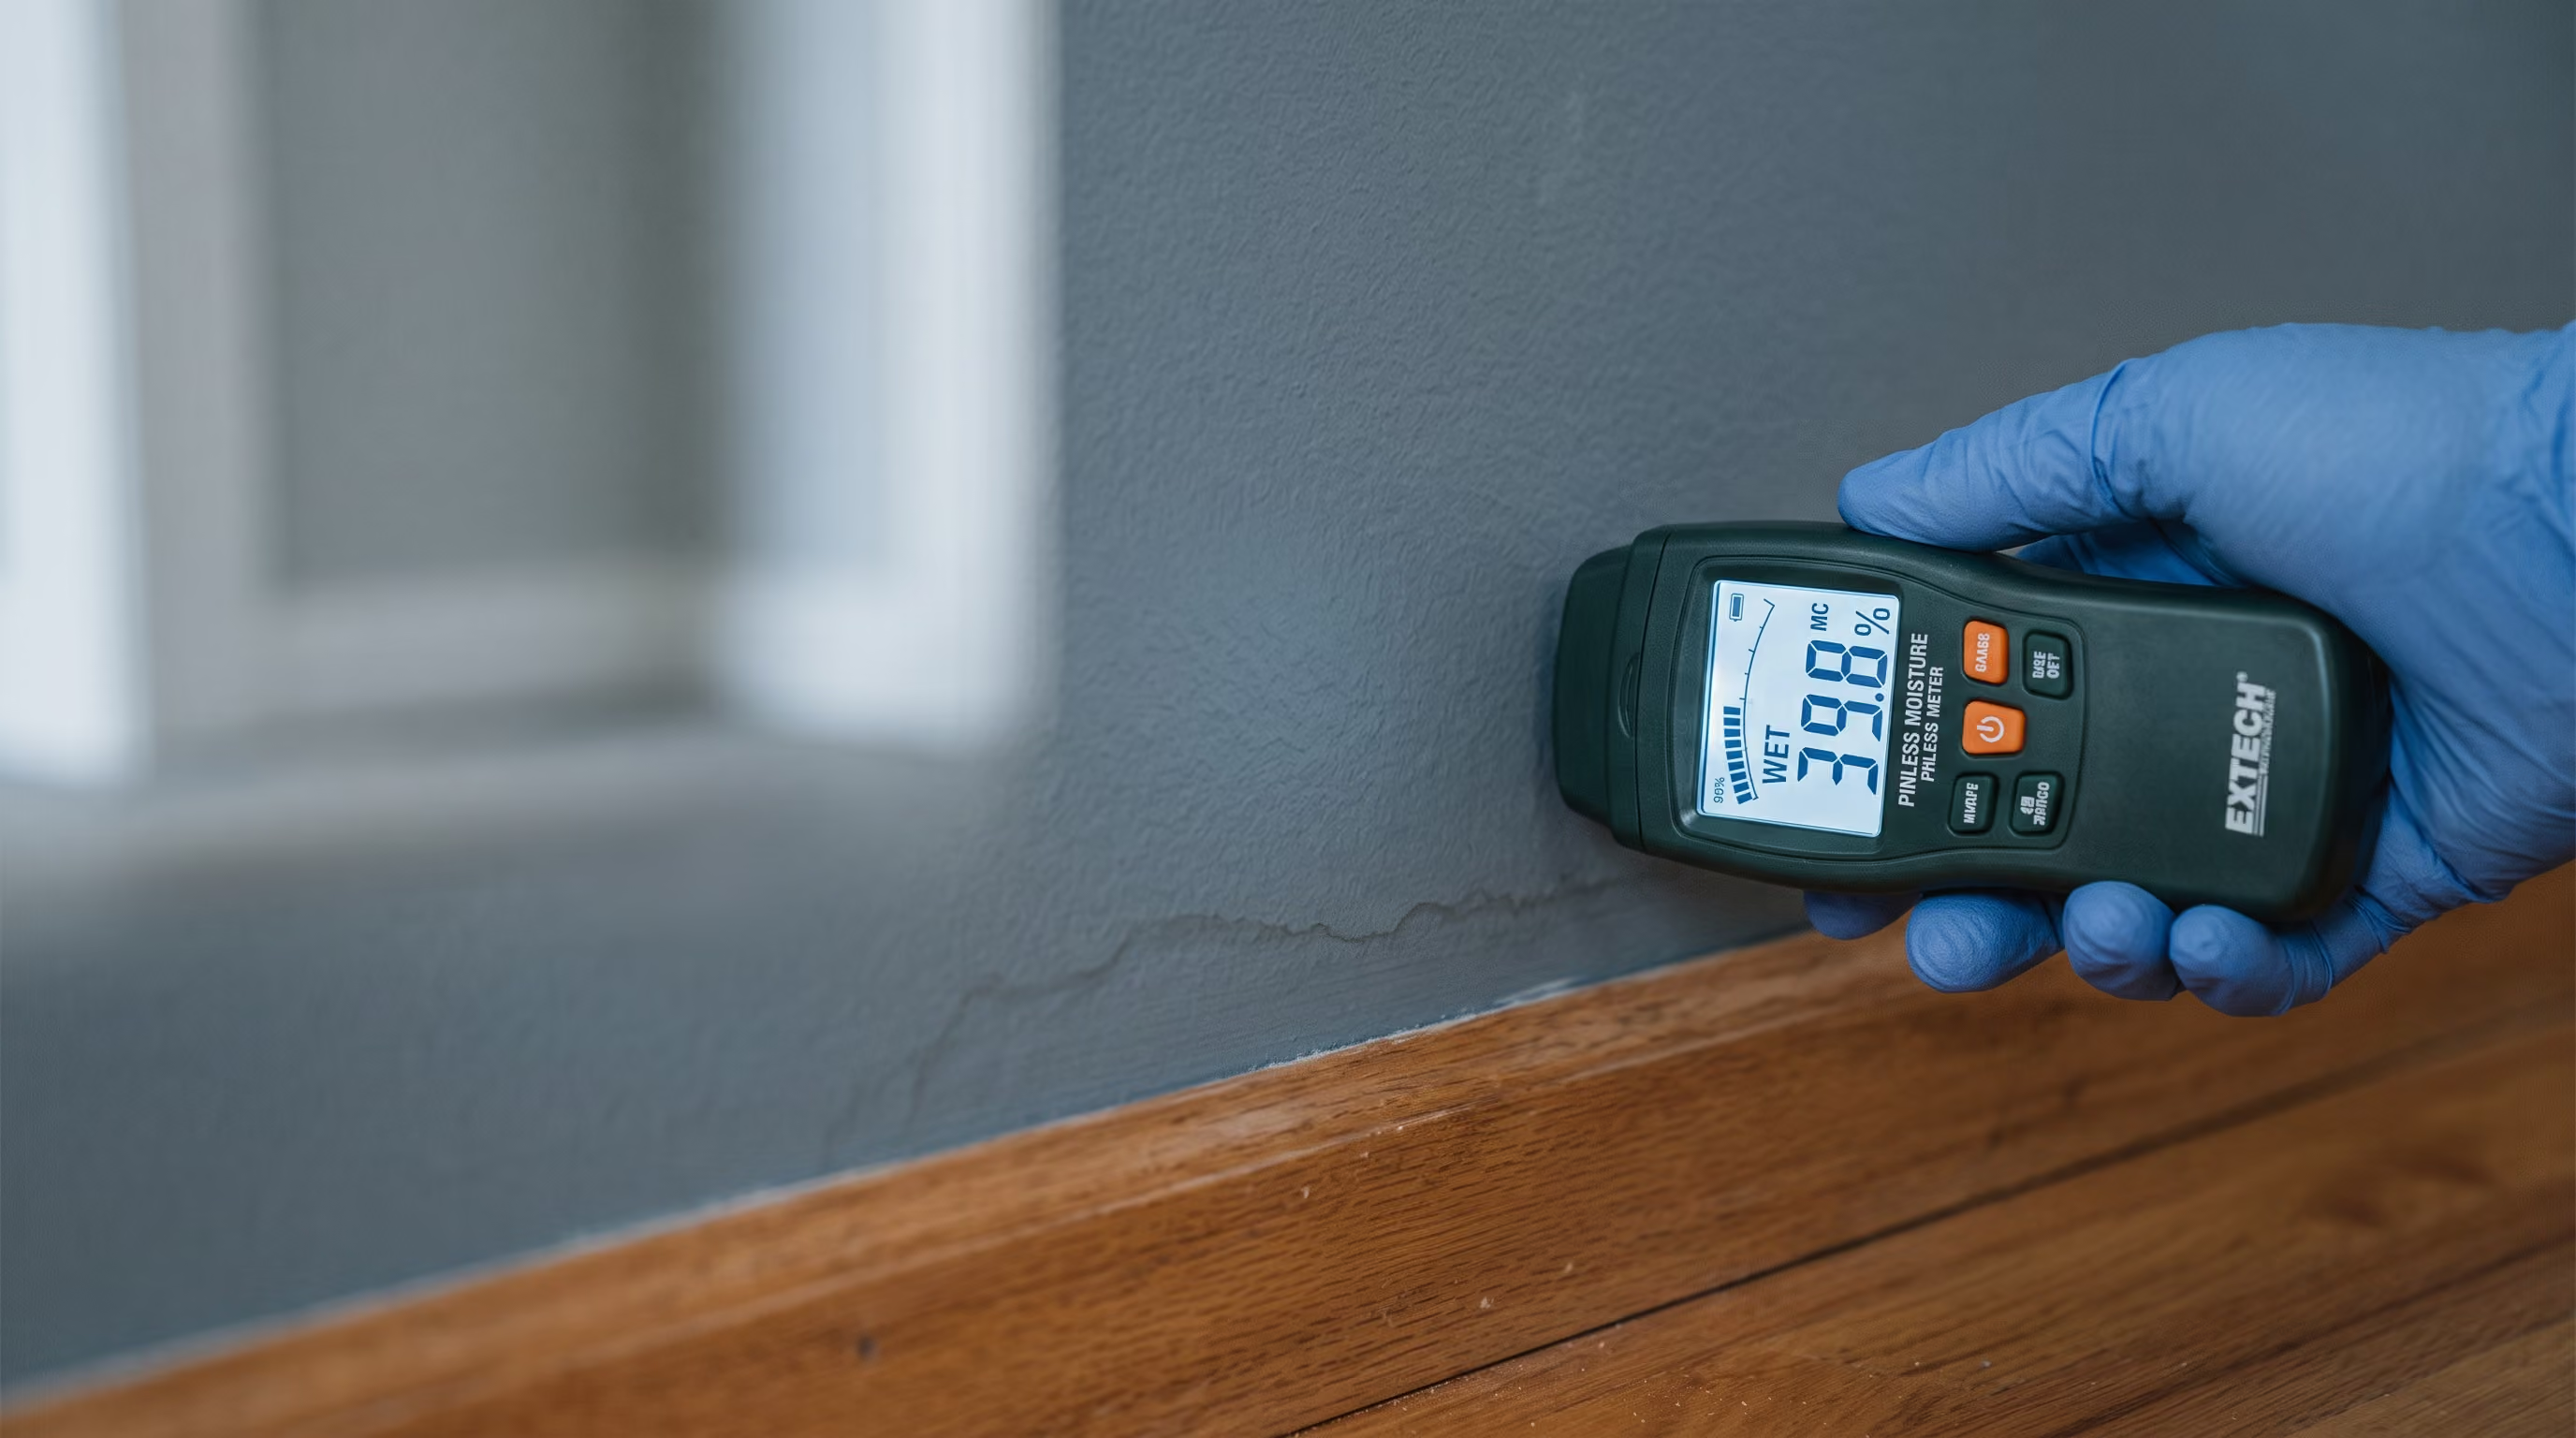
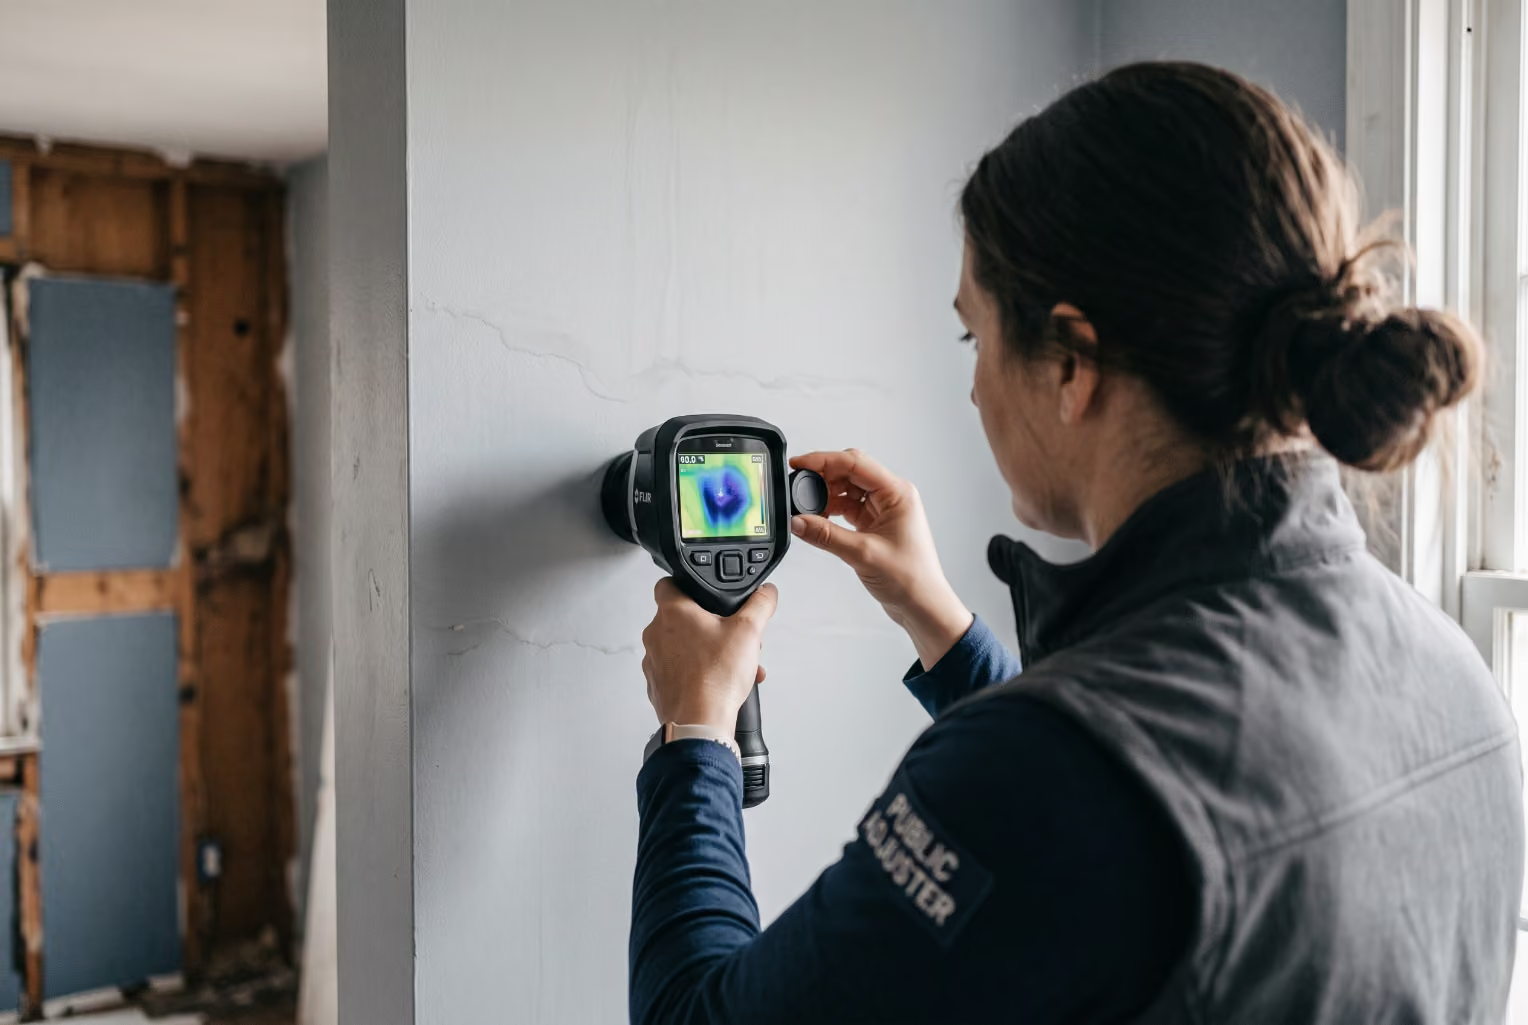
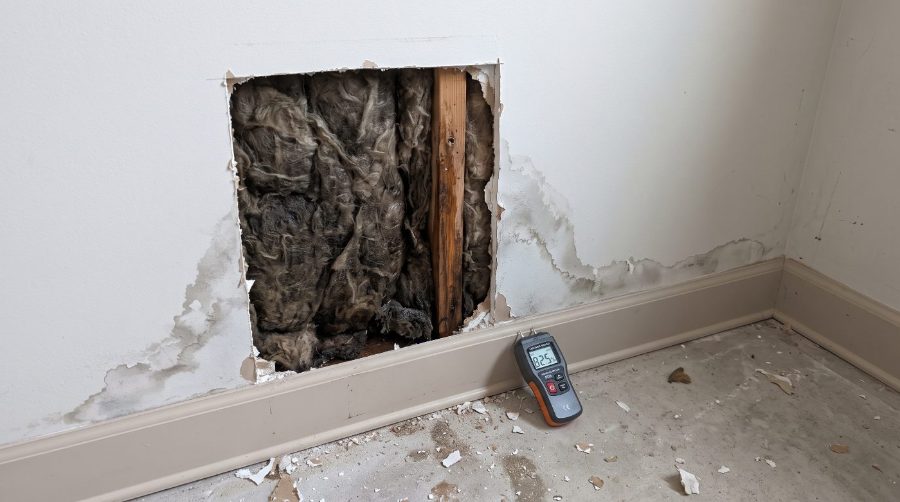
Water wicks up studs and travels along joists well past the room it started in. Meters and thermal imaging find it. A walk-through does not, because nothing on that wall looked wet.
Contents, and who restores them
A room-by-room inventory lands on the person who just lost everything. Textiles, electronics, documents and furniture each need a vendor who handles that specifically, or repairable property becomes a total loss.
What gets called mold
Most policies cap fungus and mold remediation well below the rest of the coverage. Whether wet material is written up as water damage or as mold decides which limit pays to remove it.
The estimate itself
Like a renovation you once priced yourself, the big items are there and look right. It is the missing small ones that move the number: a bathroom written in five line items instead of fifteen.
Timing
Your policy has deadlines you didn't negotiate.
Notice of loss, proof of loss, and a limit on how long you have to bring suit. All of them run from the date of loss, not from the day the insurance company gets back to you. Most people never learn what theirs are until one has already passed.
Some of those deadlines are set by state law rather than by your policy. In Michigan, here is how they work.
Right now
Photograph it before anyone cuts.
Stop the source and protect what you can, because your policy requires it and those costs are usually covered. Then, before the crew starts tearing out, photograph every room, every wall base, every cabinet. Write down where the water came from and when, while you still remember it exactly. Keep every receipt, the emergency plumber included. And do not sign anything that assigns your claim to a contractor until someone on your side has read it.
What we actually do.
We map the full moisture footprint with meters, thermal imaging and 3D scans before the drying crew finishes, because after that the evidence is in a dumpster. Then the estimate goes into Xactimate line by line, and their calls come to us.
Already have an offer? It is usually not too late.
Claims can be supplemented or reopened, and a low first offer is the most common reason people call us. If a check has already been cashed, that is not necessarily the end of it either. If the offer is fair, we will tell you that.
What this costs you.
Nothing up front. We work on a contingency fee, which means we are paid a share of what we recover for you, and not until you recover. The number goes in writing before any work starts. If we look at your claim and do not believe we can add enough to be worth our fee, we will tell you, and that conversation still costs you nothing.
A claim we handled
An offer of $79,612 on a loss that appraised at $523,331.
Appraisal settled at $523,331. The offer was $79,612.
A second-floor supply line failed and the water went down through the house. Documented floor by floor, and resolved at appraisal once the gap proved too wide to negotiate.
Tell us where the water came from.
That one answer tells us most of what we need to know about where your claim stands. No cost, no obligation.