The contents were priced as cleanable. Appraisal called them a total loss.
The loss
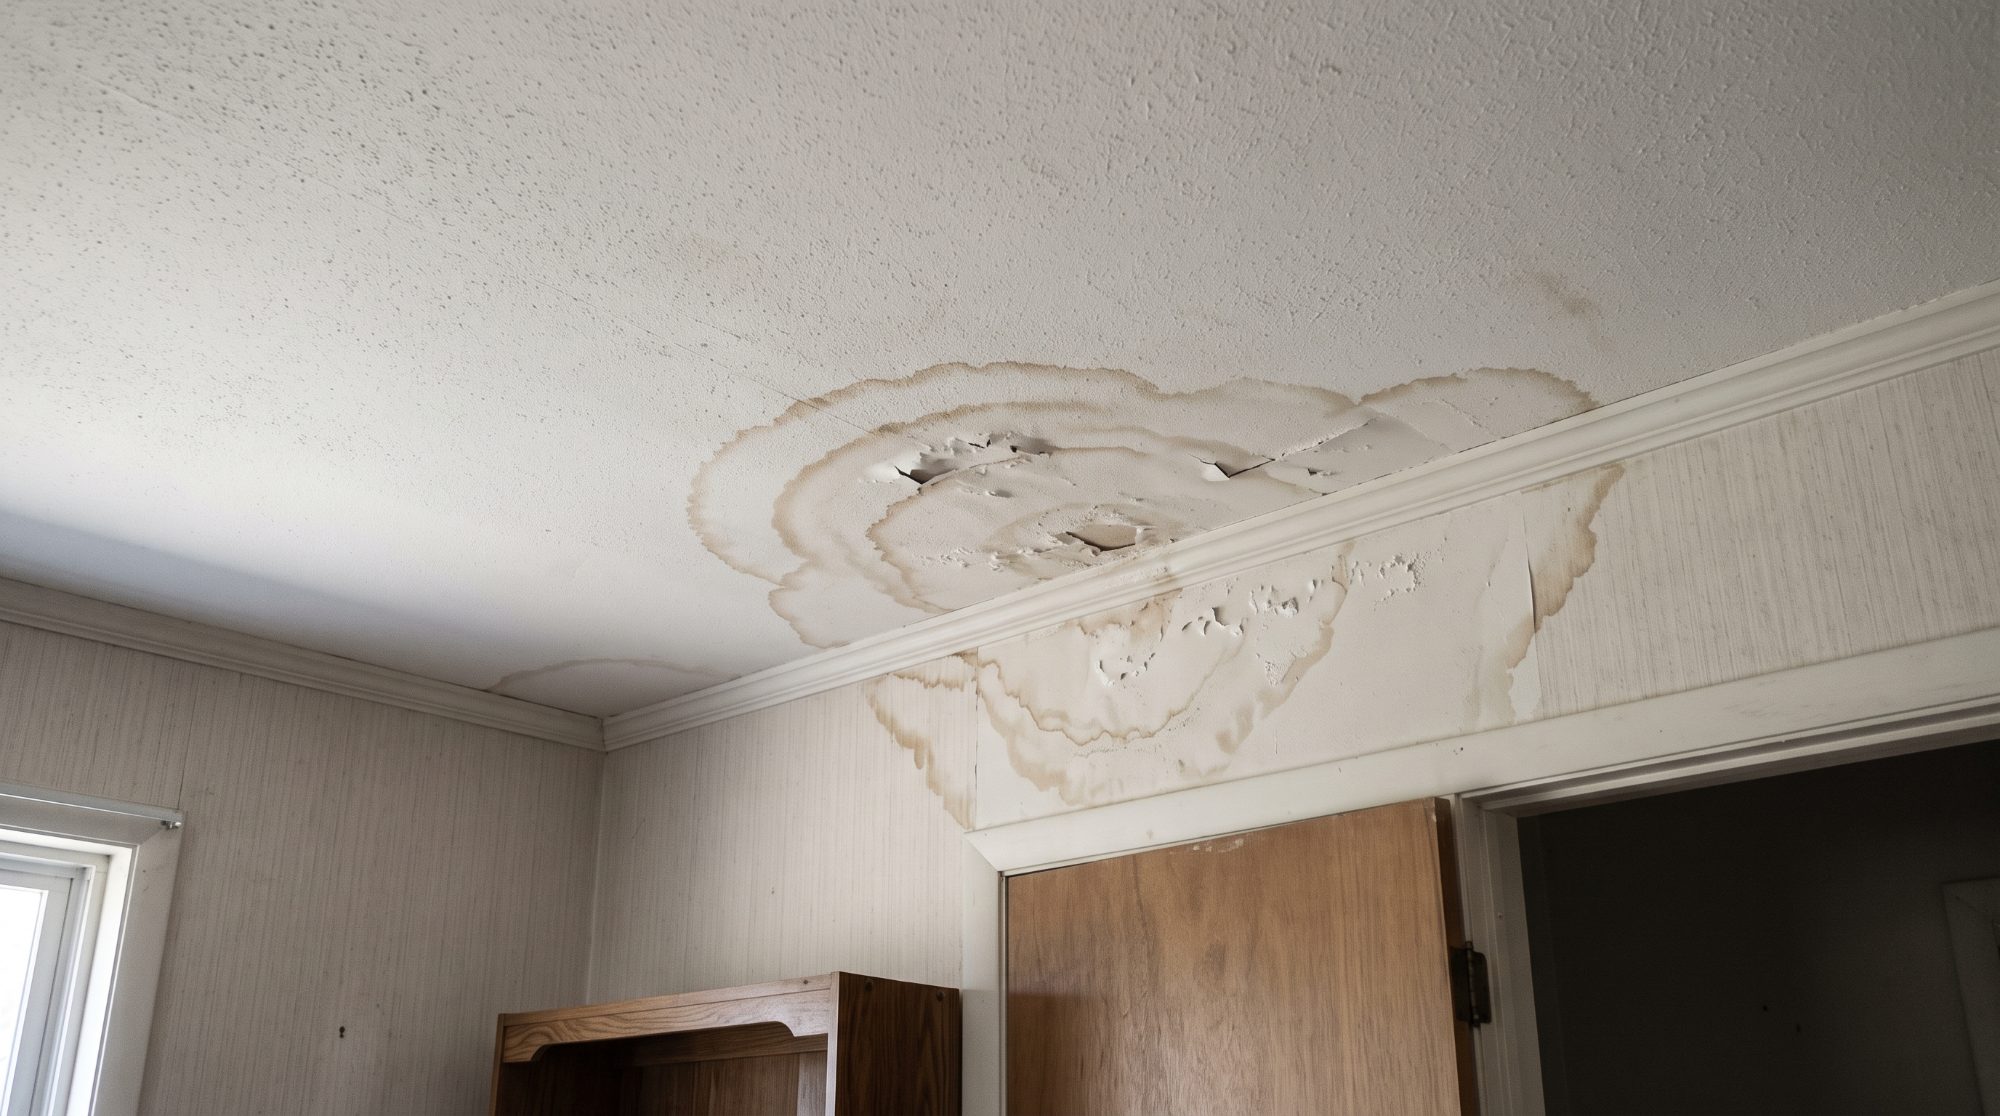
Water backed up into a Sterling Heights home and stood across the lower floor, with the family's belongings in it.
The first offer was $16,800 to repair the dwelling and $3,696 for the contents, on the basis that most of what the water had reached could be cleaned rather than replaced.
The first pass
- $16,800 for the dwelling.
- $3,696 for contents, priced as cleanable.
The full claim
- The dwelling priced from the materials actually in it.
- Contents inventoried item by item.
- Appraisal, once negotiation ended.
- Personal property reclassified as a total loss.
What we did
We measured the interior with DocuSketch, and used the homeowner's own photographs from before the loss to establish what the building materials actually were, rather than guessing from what was left of them.
Her photographs from the day of the loss did the same job for the contents. They showed what the water had reached and how long it sat, which is the difference between an item that can be cleaned and an item that has to be replaced. When the insurance company stopped negotiating, we took it to appraisal, and the personal property was reclassified as a total loss.
The outcome
The claim settled just short of the policy limit, about nine months after we were engaged. Water backup is usually written as a sublimit rather than full dwelling coverage, which is exactly why the line between cleanable and destroyed decided this one.
Identifying details are limited to protect client privacy. Figures are the insurance company's documented position and the final settlement on that claim. Every claim is different, and past results don't predict the outcome of any future claim.
Related
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.