House fire claims in Flint
What a Flint fire claim involves, and where it gets underpaid
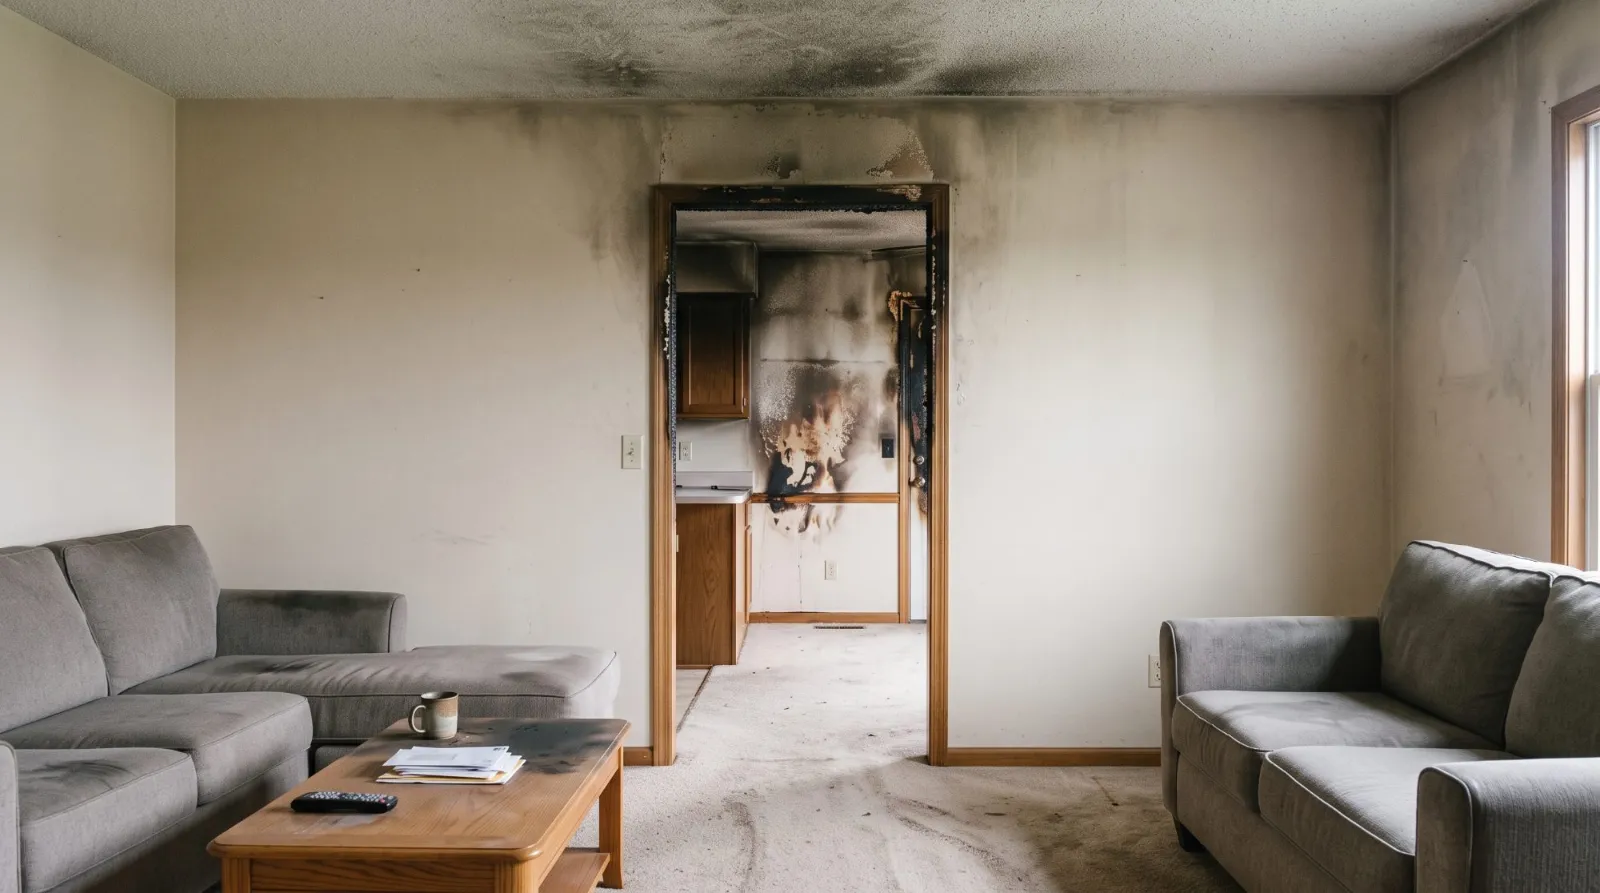
Flint's housing is old and much of it sits close together, which shapes almost every fire claim we see here. Here is what makes a Flint fire claim different, and where the money usually gets left out.
Why Flint fire claims run bigger than they look
The houses are old. Most Flint homes were built before 1960, and neighborhoods like Civic Park date to 1919 and 1920. Plaster, old framing, original trim and old wiring cost far more to put back than a quick estimate assumes. On a replacement cost policy, the claim is priced on what it costs to rebuild your house, not on what it would sell for.
Smoke travels through old construction. Old framing and ductwork carry smoke into rooms the fire never reached, the attic and the floor above included. Those rooms are where a walk-through estimate comes up short.
The fire often started in a vacant house nearby. Many Flint blocks have empty or blighted houses, and fires spread from them. Your own policy usually covers the damage to your house, inside and out. The outside scorching is easy to see. The smoke inside is the part that gets missed.
If part of the payment is held back
Michigan law lets a city hold part of a large fire settlement on a building until the building is repaired or the site is cleared, and Michigan replacement cost policies usually hold back depreciation until the work is done. Either can make the first check smaller than the claim. Ask the insurance company early whether either applies to you, and see how fire insurance claims work in Michigan for the details.
The fire report
To get the fire report in Flint, file a Freedom of Information Act request with the city. You can submit it online through the city's FOIA page, or by mail to the FOIA Coordinator at the City of Flint Department of Law. Include the address and the date of the fire. The city has five business days to respond and can extend that by ten. The insurance company will read the report closely, and so should you.
What we have seen on fires in this area
On a house fire in an older Mid-Michigan home, the insurance company offered $84,559. We documented the house room by room and the claim went to appraisal, which settled at $166,385, with interest for the time the claim took. Every claim is different, and that is not a promise about yours. It shows where the gap usually is.
Where we come in
Flint is our longest-standing office. It is on Flushing Road, a short drive from anywhere in the city. We read your policy, document the whole loss, build the estimate the way a contractor would price the rebuild, and deal with the insurance company for you. There is no fee until you recover. Here is how we handle fire and smoke damage claims.
See it on a real claim
Fire in Flint? |Talk to us before you settle.
Tell us what happened and we'll give you an honest read on where your claim stands. No cost, no obligation.