Public adjusters in Rochester, Michigan.
On May 18, 2024 a propane tank exploded at a Main Street storefront in downtown Rochester, injuring seven people, and in May 2022 a fire left a shop on East Street with extensive roof damage. More than a third of the city's homes predate 1970, and older buildings cost more to put back than a stock estimate allows.
AdjustFair works only for the policyholder, from our Ferndale office, about 16 miles south of Rochester. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Three kinds of loss drive most serious Rochester claims, and each comes in short for its own reason.
- Fire and explosions downtown. The May 2024 blast on Main Street was strong enough to bring down the neon sign of the business next door, and the May 2022 fire at Moon River Soap Company on East Street left that building with extensive roof damage. Twenty-two buildings on Main Street are more than 50 years old, and when one is damaged the neighbors often take smoke, water and impact damage too. Those buildings tend to be estimated as if they were new construction, and the tenant's build-out and lost income are left for later or left out.
- House fires. On February 15, 2023 a fire at a house on South Street spread through most of the home in high wind and partly collapsed it, and crews brought the rest down with excavation equipment. On a total loss the contents list is where money disappears, because owners are asked to rebuild years of belongings from memory. In a house built before 1970, a partial loss means tying new work into older plaster, trim and framing that an estimate often prices as drywall and stock materials.
- Trees through the roof. On June 1, 2019 strong winds brought a large tree through the roof of a home on Ludlow Avenue while the owners were on the ground floor. When a mature tree lands on an older house, the insurance company tends to price the roof, the decking and the room it entered and decline to open the ceilings and walls. Cracked rafters, racked framing and broken plumbing or wiring elsewhere in the house belong in the estimate.
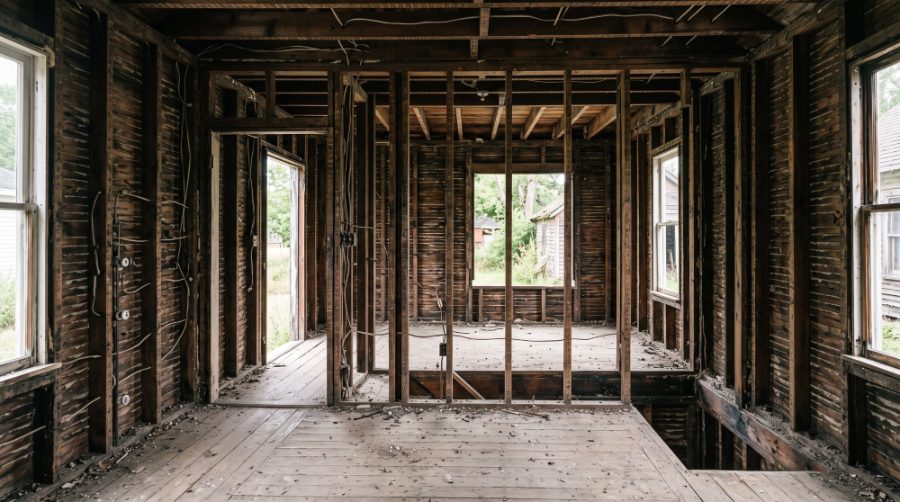
Called two days after the fire, and it never needed appraisal.
A kitchen grease fire put smoke through the house. We were engaged two days after the loss, and the scope was settled by negotiation without appraisal.
Questions we get here.
A fire next door damaged my shop in downtown Rochester. Who pays?
Usually your own commercial policy covers your inventory, fixtures, improvements and lost income, and the building owner's policy covers the structure, depending on the lease and the policies. In the older buildings along Main Street, smoke and water travel through shared walls, ceilings and ductwork, so have the space tested and document every item before anything is thrown away.
My Rochester house was built before 1970. Why does that matter on a water claim?
Older supply lines and drain pipes give out, and the water reaches plaster, hardwood and finished basements. If water came up a floor drain because the home's own line under the house broke, it started inside the house and usually gets the full policy, not the smaller limit on a back-up from an overrun public sewer. A plumber's written cause usually settles which it was.
How soon can an adjuster get to Rochester?
Rochester is about 16 miles north of our Ferndale office, so downtown and the neighborhoods around it are an easy trip for us. Call the number on this page and someone will tell you what to protect and photograph before cleanup starts, and when an adjuster can meet you at the house or the building.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.