Fire and Smoke Damage Claims in Michigan
The flames stopped somewhere.
Fire damage gets scoped by looking at what burned. But smoke moves with air, which means it reaches ductwork, wall cavities, the floor above and rooms the fire never entered. Most of what a fire costs is in the part of the house that still looks fine, and that is the part a walk-through prices at nothing.
Four fires,
Part of the house burned, and all of it smoked. The most common serious fire loss. The burned rooms are obvious and the contaminated ones are not.
Almost nothing burned, and the whole house is contaminated. A kitchen fire, a furnace puff-back, an appliance. What matters is how far it travelled. Soot carried through the ductwork, into the contents, and across rooms that had nothing to do with the fire is a serious claim, and people badly underestimate it because there is so little to look at. Smoke that stayed in the room it started in usually is not.
A total or near-total loss. A different kind of claim entirely, where the argument is about rebuilding rather than repairing.
A rental, or a building you run a business from. The building is only part of the loss. The rent you lose while it cannot be lived in, and the income a business cannot earn while it is closed, are separate coverages with their own rules and limits. That is closer to a commercial claim than a house fire, and it needs to be scoped like one.
Six ways a fire claim gets smaller than it should be
Read these against the estimate you have been handed.
Smoke goes where you cannot follow it
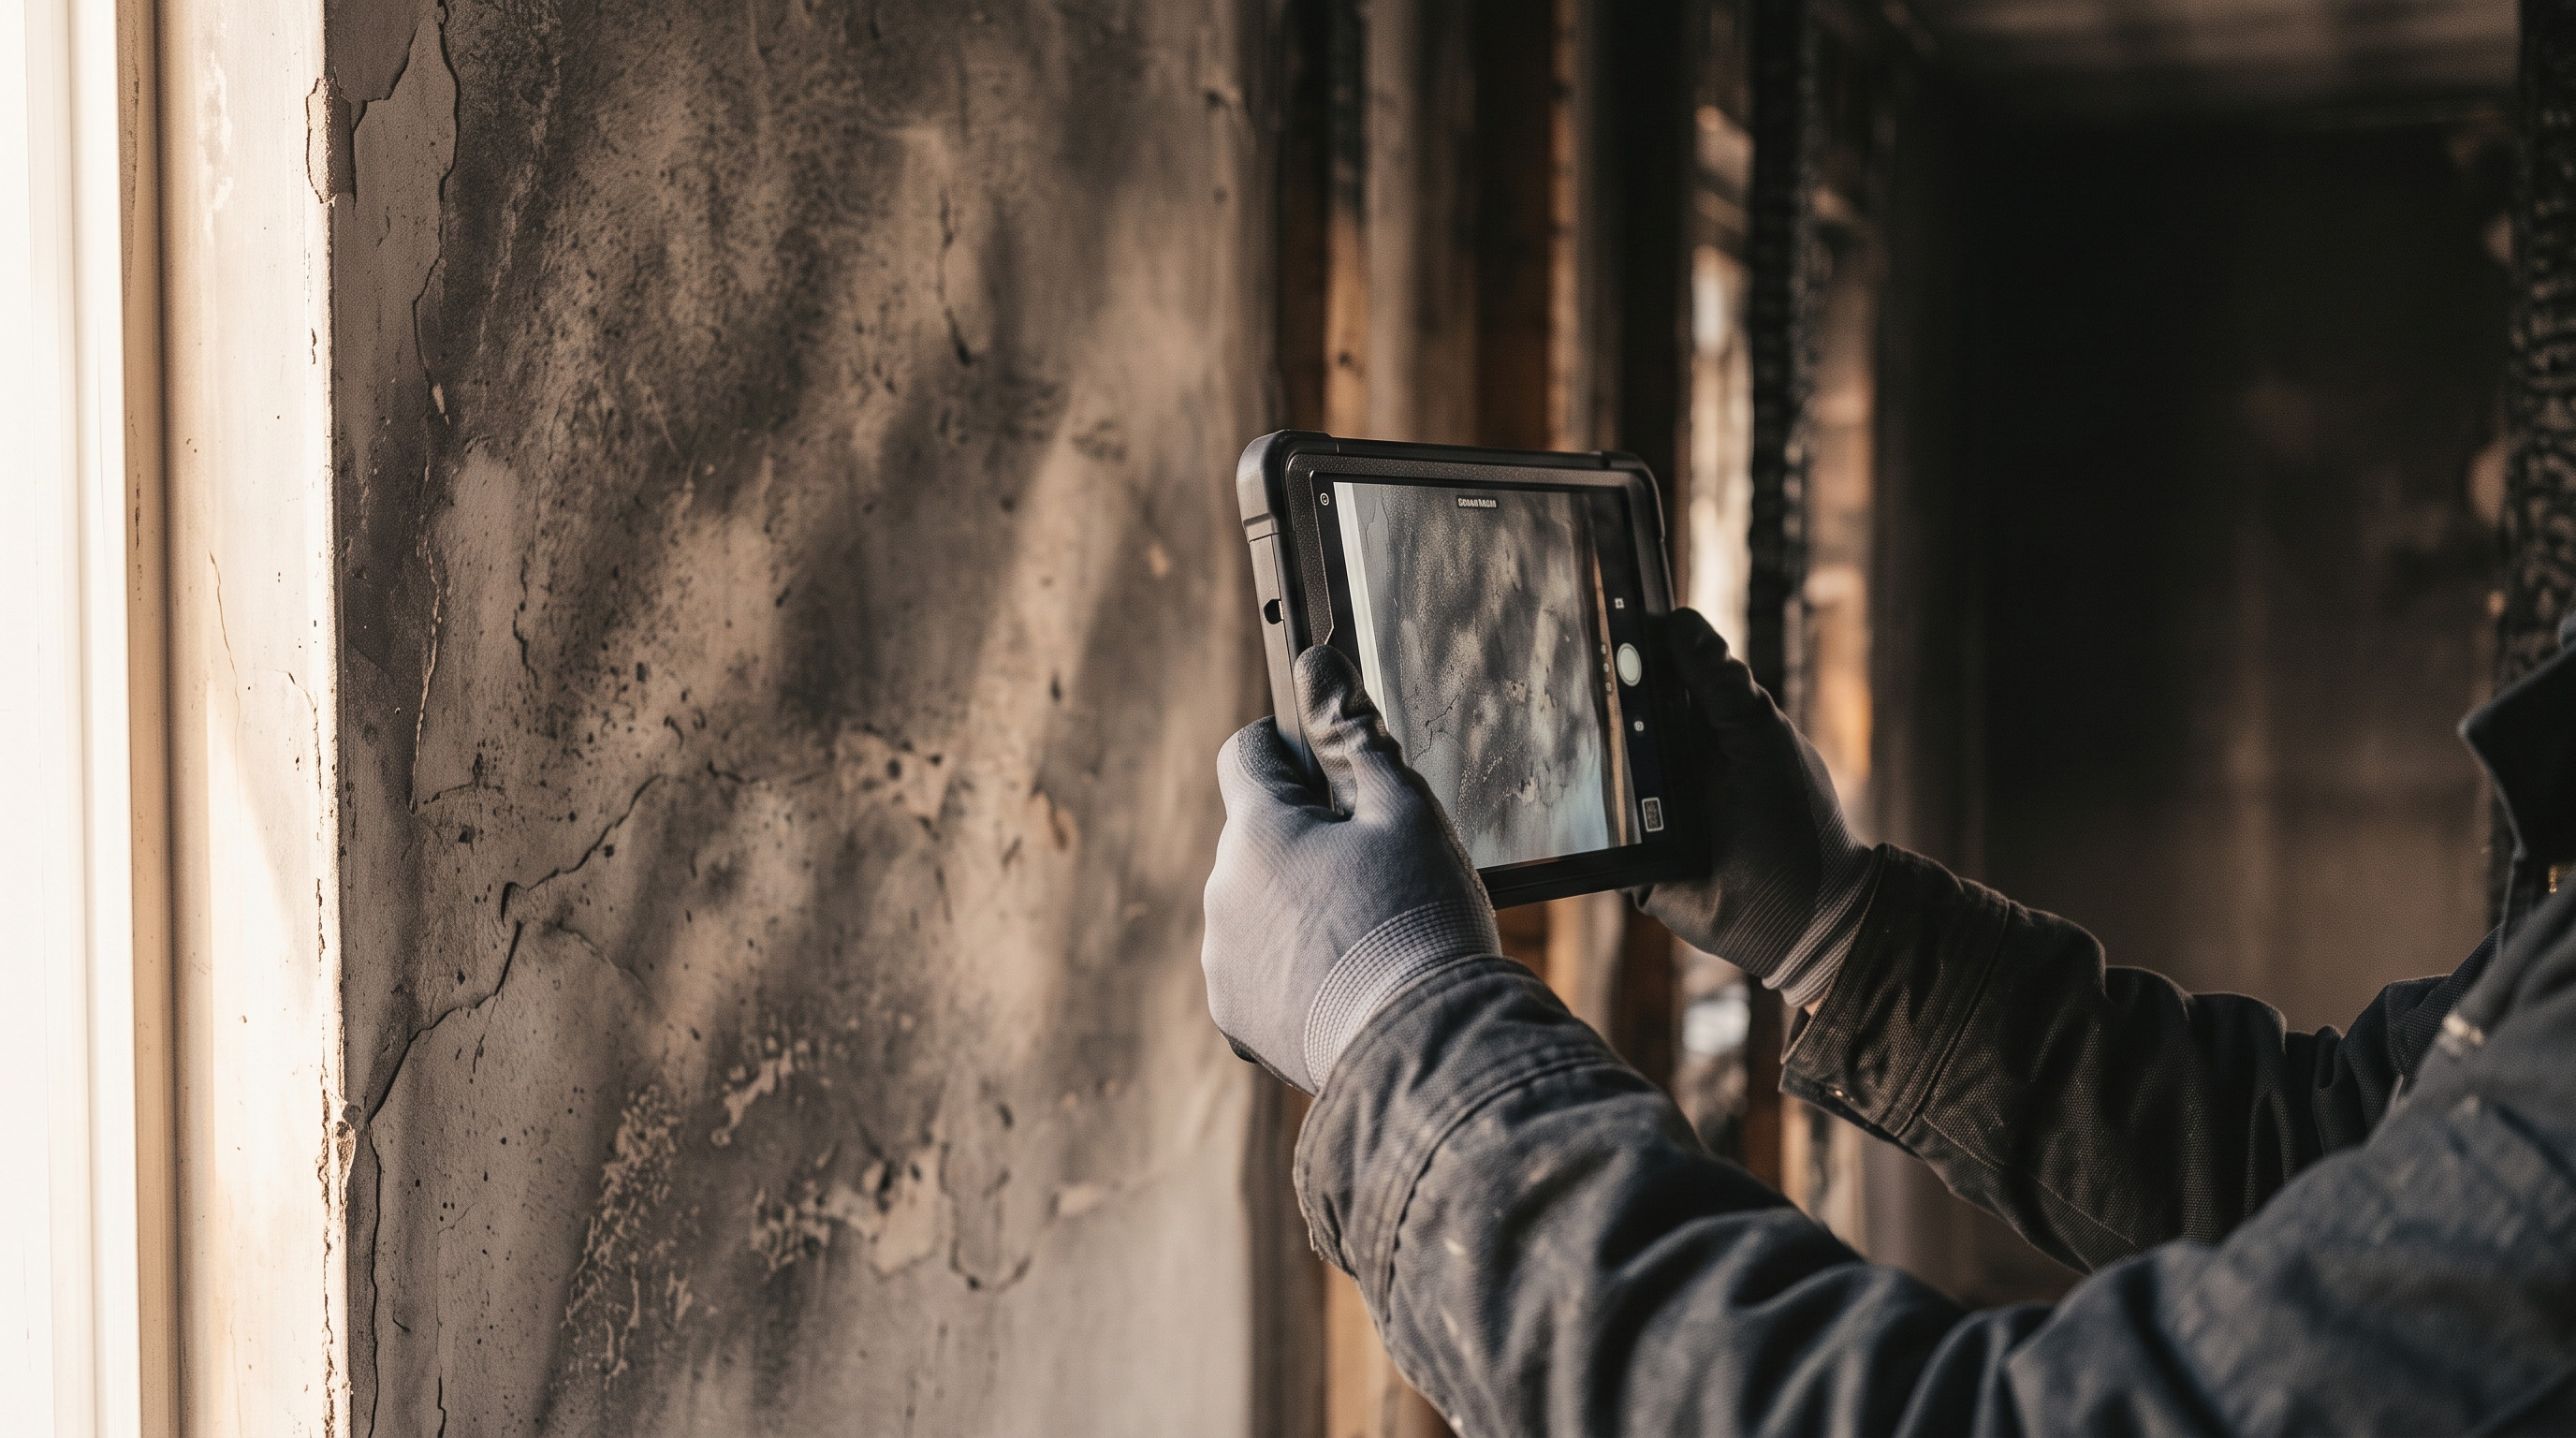
Smoke travels with air, into wall cavities, the attic, the ductwork and rooms well away from anything that burned. A scope written from what looks black prices the fire and stops.
Cleaned when it needed replacing
Sealing and deodorizing gets written where soot has gone into porous material that cannot be restored. It costs a fraction of replacing it, which is why it is on the estimate.
Plaster written as drywall
Materials recorded as something cheaper is the quietest version of this. In older Detroit housing that is a real difference in what the repair costs. Nothing looks wrong. The line is just the wrong line.
The water that put the fire out
Thousands of gallons went in under pressure and through the structure. That is a water loss living inside a fire claim, and it tends to be scoped as neither one nor the other.
Contents, and who restores them
A room-by-room inventory of what burned and what the smoke ruined, asked of the person who lost all of it, weeks later, from memory. Textiles, electronics and documents each need their own restorer.
The estimate itself
The estimate reads as thorough because the big items are all there. What is missing is the dozens of small lines under them, the way a bathroom you priced yourself came in under the real quote.
Timing
Your policy has deadlines you didn't negotiate.
Notice of loss, proof of loss, and a limit on how long you have to bring suit. All of them run from the date of loss, not from the day the insurance company gets back to you. Most people never learn what theirs are until one has already passed.
Some of those deadlines are set by state law rather than by your policy. In Michigan, here is how they work.
Right now
Photograph it before anything is moved or cleaned.
Photograph every room before anything is cleaned, moved or thrown out, including the rooms that look untouched, because those are the ones you will need evidence about later. Keep every receipt the fire causes you, hotels and meals included. If you cannot live there, your policy usually pays toward where you do, so ask for that coverage to be opened now rather than later. And do not sign a contractor's assignment of benefits, or any final settlement, until someone on your side has read it.
Working with us
What we actually do.
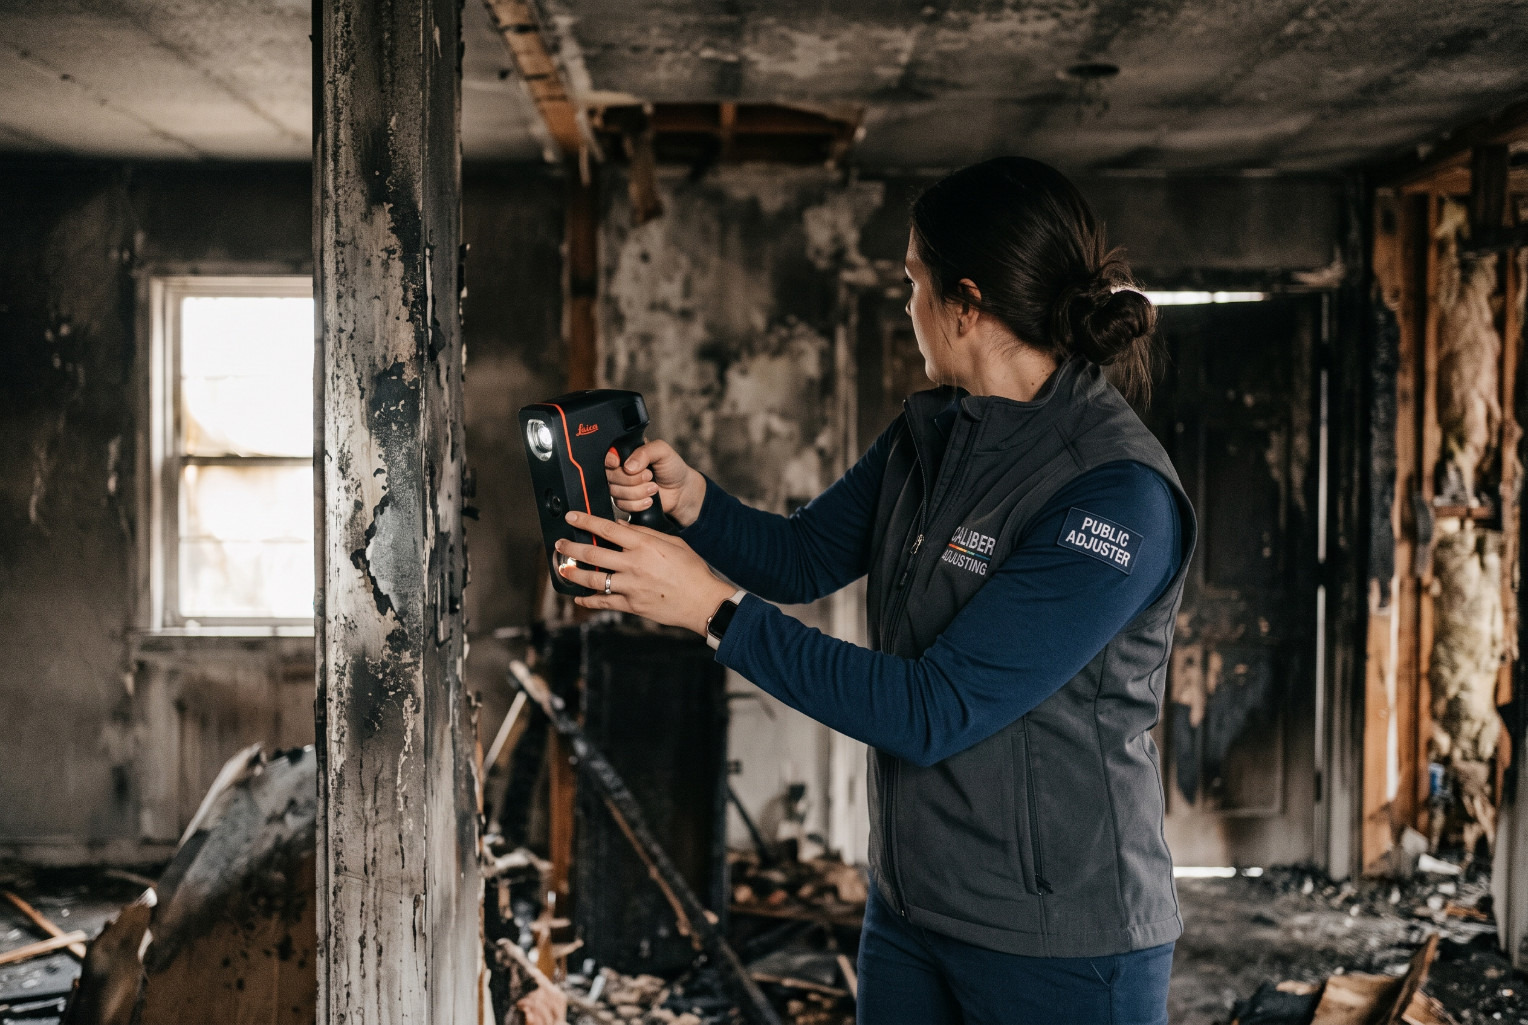
We scan every affected space in 3D, map soot and moisture room by room, and inventory the contents before anything gets cleaned. Then the estimate goes into Xactimate line by line, in the insurance company's own language, and their calls come to us.
Already have an offer? It is usually not too late.
Claims can be supplemented or reopened, and a low first offer is the most common reason people call us. If a check has already been cashed, that is not necessarily the end of it either. If the offer is fair, we will tell you that.
What this costs you.
Nothing up front. We work on a contingency fee, which means we are paid a share of what we recover for you, and not until you recover. The number goes in writing before any work starts. If we look at your claim and do not believe we can add enough to be worth our fee, we will tell you, and that conversation still costs you nothing.
Questions
Does insurance cover smoke damage in rooms the fire never reached?
Usually, yes. Smoke and soot from a covered fire are part of the fire loss wherever they ended up. The argument is rarely about whether smoke is covered. It is about whether anyone found it, because smoke inside a closed closet, the ductwork or the floor above does not show up on a quick walk-through. That is why photographs taken before any cleanup matter so much. See the first 48 hours after a house fire.
Does insurance pay for a hotel or rental after a house fire?
If the fire makes your home unlivable, most homeowners policies include additional living expense or loss of use coverage. It pays the extra cost of living somewhere else while the house is repaired, such as rent or a hotel, added mileage and higher food costs. Ask for it to be opened right away and keep every receipt. It has its own limit, so find out what yours is.
Will the insurance company hold back part of my fire settlement?
Possibly, in two ways. Most replacement cost policies pay the actual cash value first and release the held-back depreciation after the repairs are done, so the first check is smaller than the claim. And on a large building loss, Michigan law can require part of the payment to be held for the city or township until the building is repaired or the site is cleared. See how fire insurance claims work in Michigan.
My rental property had a fire. What does the policy cover?
A landlord or dwelling policy usually covers the building and, if you bought it, fair rental value: the rent you lose while the unit cannot be rented. Your tenants' belongings fall on their own renters insurance. If a business operated in the building, its lost income is a separate claim with its own proof. See commercial and business claims.
A claim we handled
A first offer of $1,872 on a fire that settled at $163,282.
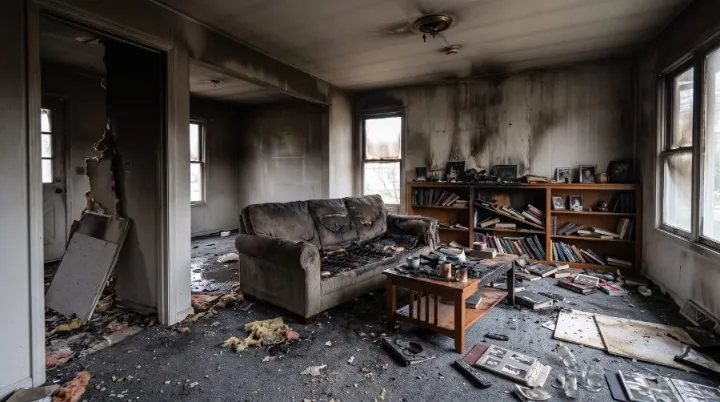
Settled at $163,282. The first offer was $1,872.
An electrical fire that started in the stairway wiring. We scanned the property room by room and brought the mitigation and vendor costs into the claim.
Read the full claimHad a fire? Talk to us before you settle.
Tell us what happened and we will give you an honest read on where your claim stands. No cost, no obligation.