Public adjusters in Sterling Heights, Michigan.
Sterling Heights grew from about 14,600 residents in 1960 to nearly 109,000 by 1980, and almost half its homes were built in the 1960s and 1970s. Where those homes have finished basements, one backup or one failed pipe reaches flooring, walls and stored belongings at the same time.
AdjustFair works only for the policyholder, from our office in Ferndale, about 10 miles southwest of the city. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Three kinds of loss do the most damage in Sterling Heights, and in each one the details decide what gets paid.
- Water in a finished basement. The median Sterling Heights home was built in 1977, and in the August 2014 storm the county executive pointed to flooding in Sterling Heights, including at city offices and the police department. Basement claims are decided in the first week, so drying records, moisture readings and photos of the paneling, carpet and built-ins before they go to the curb matter as much as the repair estimate.
- River water and backup on the same day. The Clinton River crosses the northeast part of the city; in August 2014 it reached what may have been an all-time high, and in April 2026 the city warned residents to stay clear as Dodge Park flooded. Rising surface water is usually flood and excluded from a homeowners policy, but a backup through a floor drain or a burst pipe in the same storm can be covered. Separating which water did which damage is where these claims are won or lost.
- Industrial and commercial buildings. Auto plants have anchored Sterling Heights since the 1960s, and the Stellantis assembly plant on Van Dyke alone covers about 5 million square feet. On a large building the first estimate is often written from what can be seen, and the roof structure, wall systems and mechanical equipment behind the finishes go undocumented.
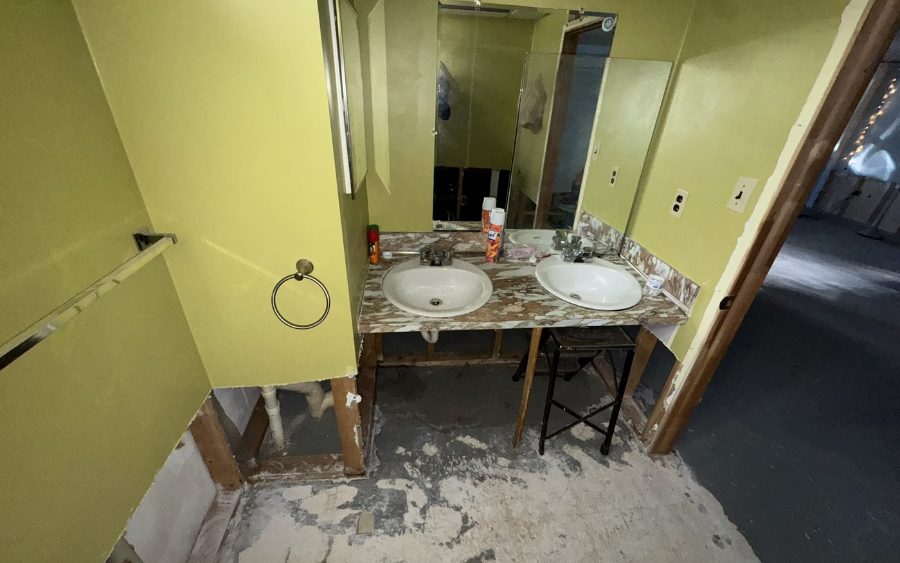
The contents were priced as cleanable. Appraisal called them a total loss.
Water backed up into a Sterling Heights home and stood across the lower floor. The first offer treated what it had touched as cleanable. Appraisal disagreed.
Questions we get here.
Is Clinton River flooding covered on a Sterling Heights homeowners policy?
Usually not as flood. Water rising from the river or across the ground normally needs a separate flood policy. A backup through the floor drain or a pipe that failed in the same storm can be a different matter, depending on the endorsements. Have the policy read before you accept a denial that treats all of the water as flood.
My Sterling Heights house is from the 1970s with a finished basement. What gets missed?
Mostly line items. A finished basement has paneling or drywall, insulation, carpet and pad, doors, trim, built-ins and often a bathroom, and estimates tend to collapse those into a handful of lines. The contents stored down there get undercounted too. We list what was actually in the room and price it that way.
How long before someone can get to Sterling Heights?
Sterling Heights is about 10 miles from our Ferndale office, close enough that an adjuster can usually be at the property quickly. Call the number on this page and we will tell you what to do first and when someone can come out to see the damage.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.