Public adjusters in Taylor, Michigan.
More than half of Taylor's homes were built in the 1950s and 1960s, and house explosions have hit Merrick, Buck Street and a townhouse off Wick Road, where DTE pointed to a gas dryer that was not hooked up properly. Older houses and shared townhouse walls both change how far damage travels and what a claim should pay.
AdjustFair works only for the policyholder, from our Ferndale office, about 17 miles northeast of Taylor. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Taylor claims tend to turn on three kinds of loss, and each has its own way of coming in under what the repair really costs.
- Explosions and fire. In July 2019 a gas explosion blew out a wall of a townhouse at Heritage Glen, and a neighbor in the same building said the whole house shook. A blast shifts framing, cracks walls and ceilings and breaks seals well beyond the room where it happened, and the insurance company often scopes only what is visibly broken. Smoke from the fire that follows can carry into the units next door, which may have claims of their own.
- Frozen and burst pipes. In the bitter cold of late December 2017, pipes burst in three of Taylor's own buildings, including City Hall, and a fire suppression line at the Lakes of Taylor Golf Club ran for over an hour, with repairs estimated above $100,000. In a 1950s or 1960s house the same damage comes from a supply line in an exterior wall, or an upstairs tub, toilet or sink that overflows into the ceiling below. Water claims are won or lost in the first week, so the drying logs, photos and moisture readings need to exist before the walls are closed.
- Commercial buildings. Taylor's commercial base runs from Southland, a regional mall with more than 100 stores, to restaurants like the one on Allen Road where, on September 29, 2026, nearly all the bricks along one wall came down. On collapse and fire claims for commercial property, the shortfall sits in the line items: shoring, engineering, tenant finishes and the systems inside the walls.
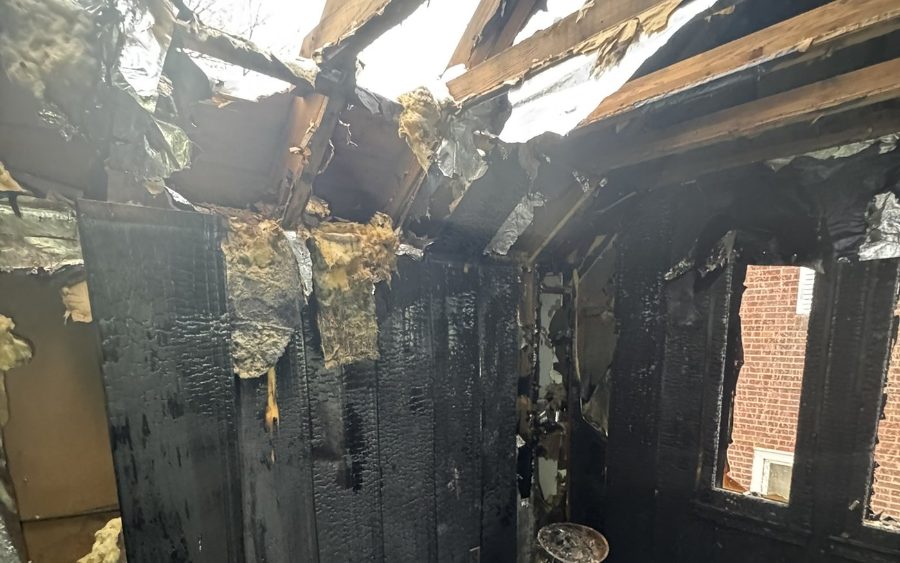
No first offer. The claim settled at the $190,000 dwelling limit.
A house fire in Detroit. We were engaged before the insurance company had put any number on the claim, documented the structure inside and out, and it settled at the dwelling limit.
Questions we get here.
A fire or explosion next door damaged my Taylor townhouse. Whose policy pays?
Usually your own, for your unit and your belongings, even though the loss started somewhere else. Depending on the association documents, parts of the building may fall under the association's master policy, so the two policies have to be read together. Document smoke, cracks and sticking doors in your unit before cleanup starts, and keep the fire department's report.
Do you handle commercial buildings in Taylor?
Yes. Restaurants, retail, offices and apartment buildings all have structure, finishes and building systems that a quick estimate tends to undercount, especially after a fire, a collapse or a burst fire suppression line. We document the building as it stood, price the repair the way a contractor would have to build it, and keep the insurance company working from that number.
How fast can someone get out to Taylor?
Taylor is about 17 miles from our Ferndale office by straight line, and the freeways make it a routine trip for our adjusters. Call the number on this page and the person who answers can tell you what to do first and when an adjuster can walk the property with you.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.