Public adjusters in Bloomfield Township, Michigan.
More than half of Bloomfield Township's homes were built before 1970, nearly all of those in the 1950s and 1960s, and the median owner-occupied home is worth about $605,000. In February 2022 fire tore through the roof of the 1922 Oakland Hills clubhouse. Older framing and custom finishes both raise what a repair here costs.
AdjustFair works only for the policyholder, from our Ferndale office, about 11 miles southeast of Bloomfield Township. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Three kinds of loss account for most serious Bloomfield Township claims, and each one tends to be underpaid in its own place.
- Fire in large custom homes. In April 2017 fire destroyed most of a home of about 15,000 square feet on Blue Heron Court, on Upper Long Lake, and the fire chief said it appeared to be a total loss. On a house that size the stone, millwork and mechanical systems get priced as builder grade when nobody documents what was there. The contents, often thousands of items, end up being listed from memory and undercounted.
- Sewage up through a basement drain. When sewage backs up through an indoor drain, the township sends a Water and Sewer employee to check whether the blockage is in the public main or the owner's private sewer lead, and if the main is flowing, the owner calls a plumber. That finding matters to the claim: water from a break in the home's own line started in the house and usually gets the full policy, while a back-up from a public main that could not carry the flow often falls under a much smaller back-up limit. Either way it is category 3 water, and in a finished basement the carpet, drywall and trim it touched have to come out, not just be dried.
- Commercial buildings and crashes into them. The Oakland Hills clubhouse was a multi-story building of about 110,000 square feet, among the largest wood structures in Michigan, and on November 6, 2025 an SUV went through the storefront of a restaurant on Telegraph near Long Lake Road, closing the building until it could be shown to be structurally sound. On commercial losses the first estimate tends to cover the visible damage and stop short of the framing, the storefront system and the income lost while the doors are closed.
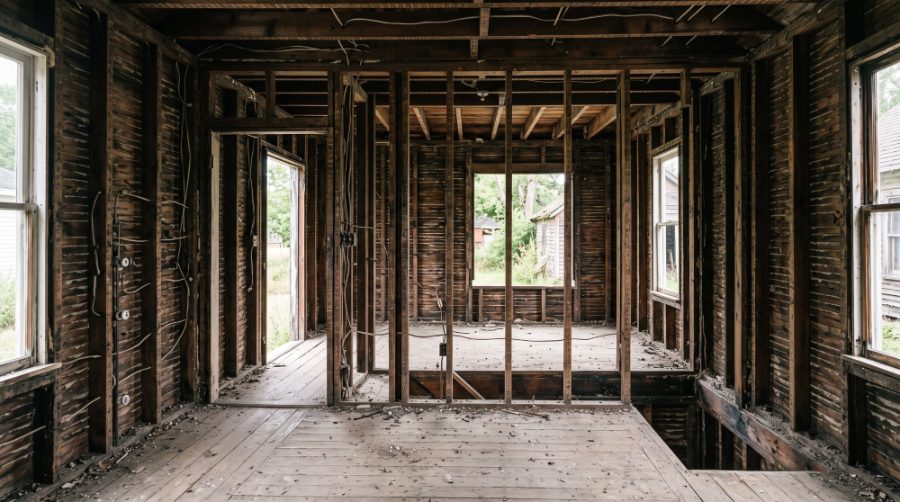
Called two days after the fire, and it never needed appraisal.
A kitchen grease fire put smoke through the house. We were engaged two days after the loss, and the scope was settled by negotiation without appraisal.
Questions we get here.
Sewage came up a floor drain in my Bloomfield Township basement. Is that a back-up?
It depends on where it started. The township will check whether the public main is clear, and if it is, the problem is in your private sewer lead. Water from a break in your own line is usually treated as starting inside the house, with the full policy, not the smaller back-up limit. Get the plumber's cause in writing and photograph everything before cleanup.
A car came through the front of my Bloomfield Township building. Where does the money come from?
Often from two places. The driver's auto policy carries Michigan's mandatory property protection coverage, which pays up to $1 million for damage a car does to buildings, and your own property policy may also respond, including lost income if you have to close, as the Telegraph Road restaurant did. Have the building shored, keep every invoice, and have both policies read.
How soon can an adjuster get to Bloomfield Township?
Bloomfield Township is about 11 miles northwest of our Ferndale office, so anywhere from Square Lake Road down to Maple is a short drive for us. Call the number on this page and someone will tell you what to protect and photograph now, and when an adjuster can come out and start documenting the damage.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.