Public adjusters in Dearborn Heights, Michigan.
Six in ten Dearborn Heights homes predate 1960, most of them built in the 1950s. On July 12, 2025 a storm brought a large tree down through a house near Annapolis and Harding, leaving it too unstable to enter. Original framing, dated finishes and months away from home all change what a claim here should pay.
AdjustFair works only for the policyholder, from our Ferndale office, about 12 miles northeast of Dearborn Heights. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Three kinds of loss drive most serious Dearborn Heights claims, and each tends to come in short for its own reason.
- Trees through the roof. In the July 2025 storm a sidewalk tree came down on a Dearborn Heights house hard enough to drop a bedroom ceiling and leave the home unsafe to enter. On impact claims the insurance company often prices the roof and the hole and declines to open the ceilings and walls, where cracked rafters and shifted framing sit. When a family is out of the house for months, living expenses can become a large part of the claim, and they need records from the first day.
- Cars and explosions through the walls. In March 2025 a car shot through the Tim Hortons drive-thru at Telegraph and Warren and into a house, wrecking the kitchen and leaving the bathroom tub leaking, and in March 2023 a house near Annapolis and Pelham was leveled in a suspected explosion that also marked the homes beside it. Estimates on these losses tend to stop at what is visible, missing the plumbing, wiring and framing the impact moved. Next door, damage that looks cosmetic deserves a proper inspection before anyone signs off on it.
- Burst pipes and overflows in 1950s houses. In late January 2025 freeze-thaw swings helped break water mains on four Dearborn Heights streets, and the same cold can split supply lines in the exterior walls of a 1950s house, while an upstairs tub, toilet or sink that overflows sends water through the ceiling below. Water that comes up a basement floor drain because the home's own aging line collapsed or broke is a fill-up that started in the house and usually gets the full policy, not the lower limit on a back-up, where the city system is overrun by heavy rain, and a short plumber's report usually settles which it was. The drying logs, photos and moisture readings from the first week decide most water claims.
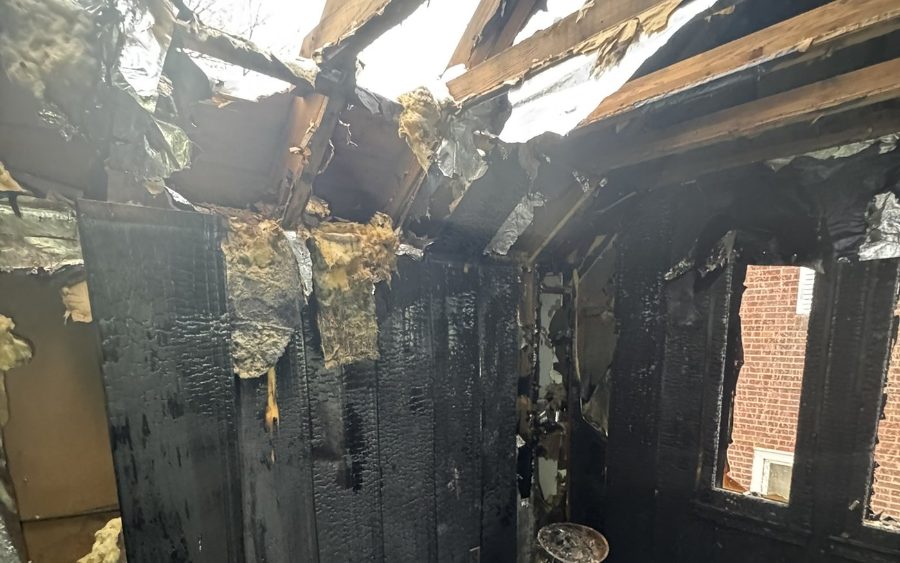
No first offer. The claim settled at the $190,000 dwelling limit.
A house fire in Detroit. We were engaged before the insurance company had put any number on the claim, documented the structure inside and out, and it settled at the dwelling limit.
Questions we get here.
A storm put a city tree through my Dearborn Heights roof. Does my own policy cover it?
Usually, yes. Damage from a falling tree is normally a claim under your own homeowners policy, whoever owns the tree, and any question about the city is separate. Photograph the tree, the roof and every room below before cleanup starts, keep the removal invoices, and do not let the estimate stop at the roofline if ceilings cracked or doors stopped closing.
My Dearborn Heights house was built in the 1950s. Why does that matter on a claim?
Houses from that decade often have original framing, older wiring and plumbing, and finishes that are no longer stocked, and every repair has to tie into them. Estimates usually miss on the count of line items, not the prices: a bathroom written in five lines instead of fifteen, original trim priced as stock. We document what the house actually has and price the repair that way.
How fast can someone reach a Dearborn Heights property?
Dearborn Heights is about 12 miles from our Ferndale office, so the north end and the south end are both an easy trip for us. Call the number on this page and you will reach someone who can explain the next steps and tell you when an adjuster can walk the property with you.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.