Public adjusters in Ann Arbor, Michigan.
Early on April 15, 2026, an EF-1 tornado with 110 mph winds crossed Ann Arbor through Veterans Memorial Park, bringing trees down on homes. Three in ten homes here were built before 1960, and more than half are rented. Old houses, big trees and rentals all shape the claim.
AdjustFair works only for the policyholder, and we come to Ann Arbor for serious losses from our Ferndale office, about 34 miles east. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Three kinds of loss drive most serious Ann Arbor claims, and each tends to be underpaid in a particular way.
- Trees through the roof. The April 2026 tornado uprooted and snapped numerous trees from Jackson Avenue into the neighborhoods around Veterans Memorial Park, and trees came down on homes. On an impact claim the insurance company often pays for the roof and resists opening the ceilings and walls below, where cracked rafters, split plaster and wet insulation sit. That damage belongs in the estimate, and it is easier to prove before the debris is hauled away.
- Fire and smoke in older houses. The Old West Side's 19th-century streetscape survives almost intact, and in September 2021 a home built in 1880 on Main Street near Pauline Boulevard burned. In houses that old, smoke travels inside wall cavities and old ductwork, and plaster, wood floors and original trim cost far more to restore than the drywall and stock materials an estimate tends to assume.
- Burst pipes and overflows in rentals. With more than half of Ann Arbor's homes rented, many water losses start in another unit: an upstairs tub or toilet that overflows, or a supply line that splits while an apartment sits empty. In the older houses near downtown, water that rises through a basement floor drain because the home's own aging drain line broke is a fill-up that started in the house and usually gets the full policy, not the lower limit on a sewer back-up driven by heavy rain, and the plumber's written cause usually decides it. Either way, the drying logs, photos and moisture readings from the first week carry the claim.
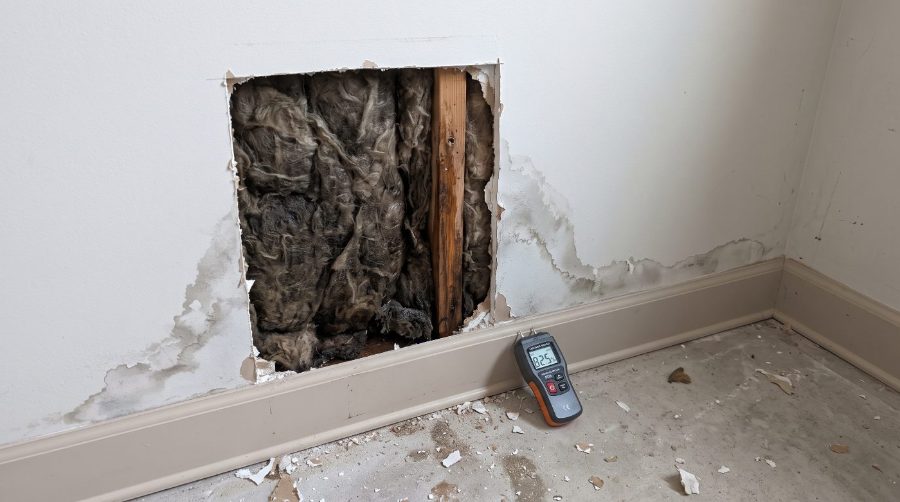
An offer of $79,612 on a loss that appraised at $523,331.
A second-floor supply line failed and the water went down through the house. Documented floor by floor, and resolved at appraisal once the gap proved too wide to negotiate.
Questions we get here.
I own a rental house in Ann Arbor. Whose policy pays after a fire or burst pipe?
Usually the owner's policy covers the building and, depending on the policy, the rent lost while it is repaired, and each tenant's renters policy covers their own belongings. Owners often see the estimate written for a basic rental finish rather than what is really in the house. We document the building as it stood and price the repair that way.
A tree from the April 2026 tornado hit my Ann Arbor house and the claim is paid. Is it too late to look again?
Often not. Many policies allow a supplemental claim when damage was missed, though deadlines vary by policy, so check yours now. Cracked framing, ceiling damage and wet insulation regularly surface weeks after the roof is patched. Gather the photos, invoices and the insurance company's estimate, and have the claim reviewed against what is actually wrong with the house.
Do you really come out to Ann Arbor from Ferndale?
For serious losses, yes. Ann Arbor is about 34 miles from our office, so we are not around the corner, and we will not pretend otherwise. On a large fire, water or tree claim, an adjuster comes to the property to inspect and document it in person. Call the number on this page to talk through the loss and plan the visit.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.