Public adjusters in Northville and Plymouth, Michigan.
About half the homes in the City of Plymouth were built before 1960, and Northville's historic district holds houses going back to about 1835. In the townships, the median home is worth about $400,000 in Plymouth Township and over $550,000 in Northville Township. Old plaster, original woodwork and large custom homes all raise what a loss here costs.
AdjustFair works only for the policyholder, from our Ferndale office, about 18 miles to the east. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Serious claims in Northville, Plymouth and the two townships tend to follow three patterns, and each one comes up short in its own way.
- Fire and smoke. In May 2026 a fire at Hines Park Place Apartments in Plymouth Township damaged about eight units in one building and sent smoke into 16 units in a second. Smoke rides through attics, wall cavities and ductwork well past the rooms that burned, in a prewar Plymouth house as much as an apartment block. An estimate that stops at the char line leaves the cleaning, sealing and rebuilding of everything else unpaid.
- Trees and limbs through the roof. On the night of September 2, 2026, police reported numerous large tree branches down around the City of Plymouth, and an August 2023 storm uprooted trees and stripped shingles just west of town. When a heavy limb lands on a roof, the insurance company tends to price the tarp, decking and shingles and resist opening the ceilings below, where cracked rafters and wet insulation sit. In a plaster house the cracking runs well past the point of impact.
- Burst pipes and overflows in older houses. A split supply line in an outside wall, or an upstairs tub or toilet that runs over, can soak two floors and a finished basement, and the estimate often prices the plaster as drywall and the bathroom in a handful of lines. Water that comes up a basement floor drain because the home's own old drain line collapsed is a fill-up that started in the house and usually gets the full policy, not the lower limit on a sewer back-up caused by heavy rain, and a short written plumber's report usually settles which one it is.
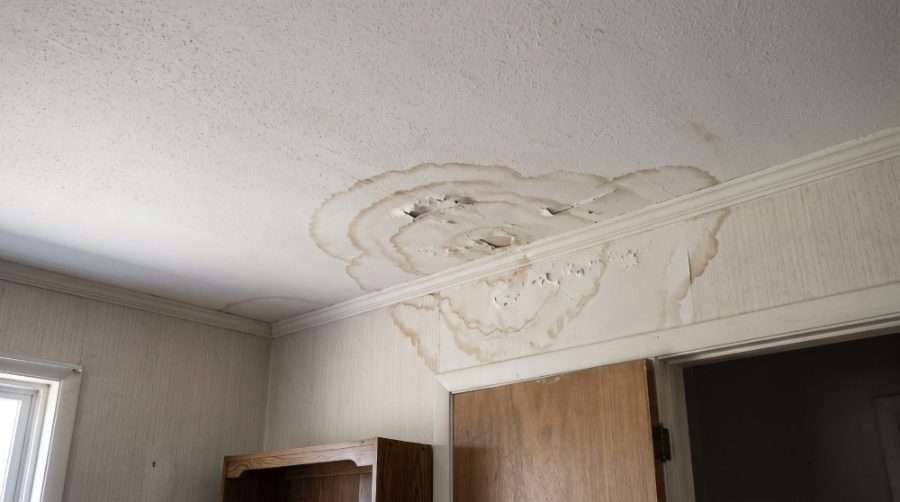
Five months in, the claim had not moved. Appraisal moved it.
A supply line failed under the kitchen island, and the claim then sat for five months. Documented with DocuSketch and vendor pricing, and resolved at appraisal.
Questions we get here.
Our house is in Northville's historic district. Does that change the claim?
It can. Original siding, trim, windows and plaster cost more to put back than the stock materials an estimate usually starts from, and the city's Historic District Commission reviews exterior changes, alterations and demolition in the district. Whether the policy pays for those added costs depends on its wording, so document the original materials before anything is torn out.
We have a large home in Northville Township. What gets missed on a big claim?
Mostly the details. Large and custom homes often get estimated with builder-grade cabinets, trim and flooring, and the contents list stops well short of what was in the house. With the township's median home worth over $550,000, the estimate should match the house. We document what was actually there, room by room, and price it that way.
How soon can someone get out to Northville or Plymouth?
Both sit about 18 miles west of our Ferndale office, an easy trip for our adjusters. Call the number on this page, tell us what happened, and we will walk you through the next few days and set a time to look at the property with you.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.