Public adjusters in Canton, Michigan.
More than nine in ten Canton homes were built in 1970 or later, and the median home is worth about $372,000. On November 30, 2025, a fire on Fredricksburg Street left one house a complete loss. Newer is not cheap to fix: finishes, cabinetry and contents add up fast when fire or water runs through them.
AdjustFair works only for the policyholder, from our Ferndale office, about 21 miles to the northeast. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Most serious Canton claims fall into one of three groups, and each has a familiar way of coming in short.
- Fire and smoke in houses and attached units. The November 2025 house fire on Fredricksburg Street was declared a complete loss, and in 2019 a fire at The Crossings apartments near I-275 and Joy Road climbed into the attic and displaced about 16 families. Smoke moves through shared attics, stairwells and ductwork, so an estimate that stops at the burned rooms leaves the rest of the home uncleaned and unsealed. On a total loss, the money is in the full rebuild and a contents list that runs to thousands of items.
- Burst pipes, failed supply lines and overflows. Homes built from the 1970s through the 2000s are now old enough for water heaters, washer hoses and toilet supply lines to give out, and an upstairs tub or toilet that overflows can run through a finished ceiling into the rooms below. The insurance company may call a failed line long-term leakage, and the estimate tends to write a bathroom in a few lines instead of the dozen or more it takes to rebuild. The plumber's written cause and the drying records from the first week usually decide what gets paid.
- Vehicles into buildings. In March 2024 an SUV went nearly 50 feet into the Walmart on Ford Road, and in May 2026 a pickup struck Canton City Market near Sheldon Road. On an impact claim the visible wall gets priced, but racked framing, a cracked slab and damaged storefront systems often do not, because the insurance company declines to open what it cannot see. More than one policy can be involved, which is worth sorting out early.
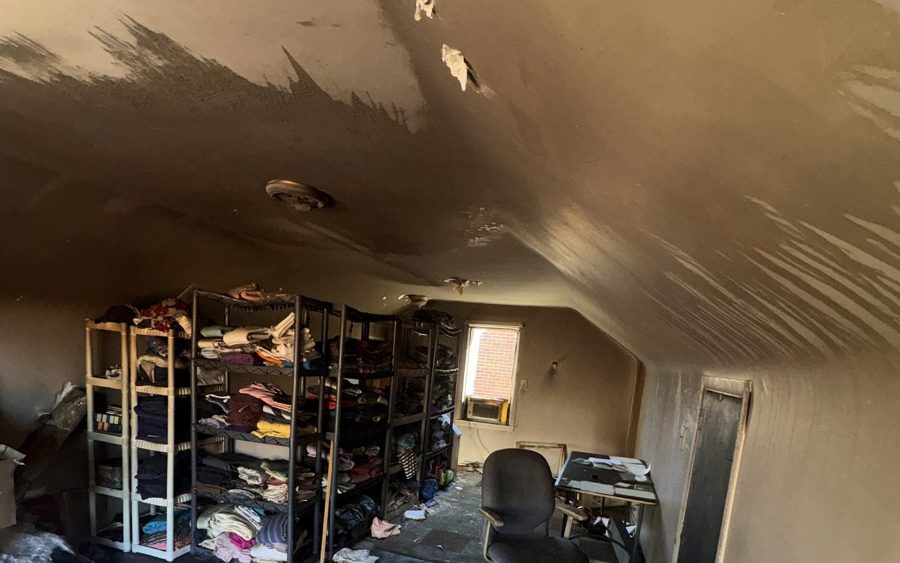
We arrived at the inspection with the estimate already written.
A house fire in Detroit. We were engaged before the insurance company inspected, and turned up to that inspection holding a finished itemized estimate.
Questions we get here.
My Canton home is a total loss after a fire. What should I do first?
Get the fire department's report, photograph what is left, and do not sign a quick settlement before the policy is read. Depending on the policy, the insurance company still owes the full rebuild, debris removal, additional living expense and the contents, which on a two-story family home can run to thousands of items. We build that list room by room.
Water came through the ceiling from an upstairs bathroom in my Canton house. Is that covered?
Usually, when it is sudden: a tub or toilet that overflowed, a supply line that burst, a water heater that let go. Stop the water, photograph everything before it is torn out, and get a written cause from the plumber. If the insurance company argues the leak was slow, the first week of drying records and moisture readings often settles it.
How long does it take to get someone out to Canton?
Canton is about 21 miles from our Ferndale office, a regular trip for our adjusters rather than a special one. Call the number on this page and you will reach someone who can tell you what to protect today and when an adjuster can be at the house or building to walk it with you.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.