Public adjusters in Madison Heights, Michigan.
About four in ten Madison Heights homes went up in the 1950s, and the city's seven industrial parks cover about 10 million square feet. In the September 3, 2026 storms a tree crashed into one family's house, destroying the living room, kitchen and bathroom. Post-war houses and working buildings both shape what a claim costs.
AdjustFair works only for the policyholder, from our Ferndale office, about 4 miles southwest of Madison Heights. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Most serious Madison Heights claims start with one of three losses, and each has its own way of coming in short.
- Trees through the roof. On July 23, 2024 a large tree uprooted near Cynthia Avenue and Milton Street and nearly went completely through a house, and in the September 3, 2026 storms another came through one resident's bedroom. When a tree lands on a 1950s house, the insurance company tends to price the roof and the room it entered and decline to open the rest. Cracked rafters, racked walls and the rain that ran in before the tarp went on belong in the estimate too.
- Fire in industrial and commercial buildings. In December 2021 a three-alarm fire destroyed the Skyline screen printing and embroidery building, about 20,000 square feet on Edward Street near 14 Mile and John R, with the back wall collapsing first. In September 2016 a fire in one washing room at the Kars Nuts plant on 14 Mile left smoke damage through the entire building. On a working building the gap often sits in the equipment, inventory and lost income, and in the parts of the structure the flames never reached but the smoke did.
- House fires and the contents inside. During the same September 2026 storms a fire at a house on Groveland Street destroyed everything in one room, left melted wiring and a hole in the ceiling, and sent embers into yards a block away. In March 2018 oxygen tanks caught in a house fire on West Hudson near I-75 set off explosions and left the home uninhabitable. On fires like these the contents are usually where the claim comes in short, because owners are left to list a room's worth of tools, bikes, books and keepsakes from memory.
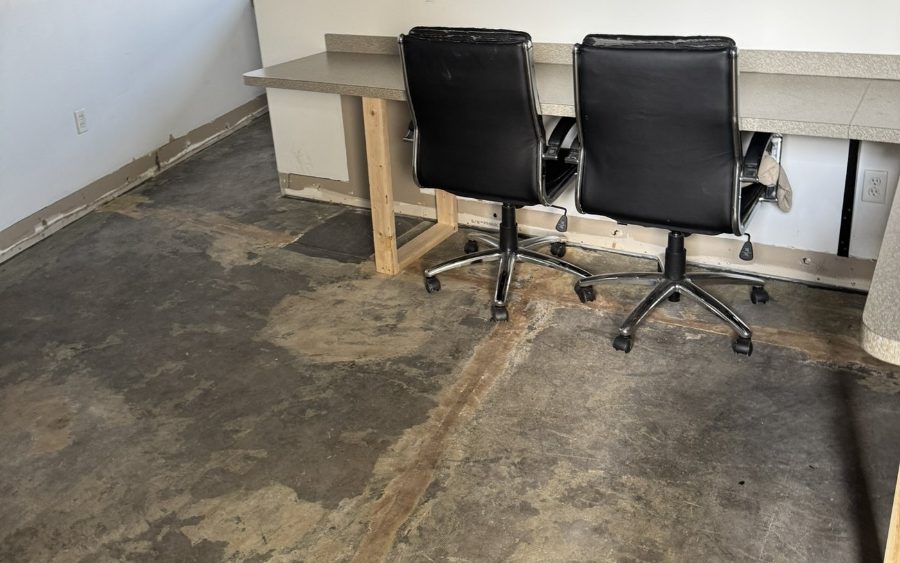
An offer of $11,630 on a commercial water loss that settled at $113,600.
Water through a Royal Oak office. The scope on the table stopped well short of the building. We itemized it, backed the materials with lab reports, and settled in three months.
Questions we get here.
Our Madison Heights shop is in an industrial building off Stephenson Highway. What does a fire claim cover?
Usually two policies are involved. The landlord's policy generally covers the building, and your own commercial policy covers your machinery, stock, tenant improvements and, if you bought it, the income lost while you are shut down. Equipment that looks fine after a fire can still carry soot and corrosive residue, so have it inspected and keep every damaged item until it has been documented.
My Madison Heights house was built in the 1950s. What gets left out of the estimate?
Mostly the parts that are hard to see. Houses from the decade the city incorporated often have plaster, hardwood under the carpet, and original wiring and plumbing that every repair has to tie into. A first estimate tends to fold those into a few general lines. We walk the house room by room, list what is actually there, and price each item.
How soon can an adjuster reach Madison Heights?
Quickly. Madison Heights is about 4 miles from our Ferndale office, just across I-696, so everything from the 10 Mile industrial area up to 14 Mile is close for us. Call the number on this page and someone will tell you what to photograph and save before cleanup starts, and when an adjuster can walk the house or the building with you.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.