Public adjusters in Ferndale, Michigan.
More than four in ten Ferndale homes were built before 1940, and on January 29, 2026 a fire near Nine Mile and Pinecrest left one house beyond saving and damaged the homes on both sides. On lots this tight one fire can become three claims, and plaster and original framing cost more to rebuild than most estimates allow.
AdjustFair works only for the policyholder, from our office on Woodward Avenue, right here in Ferndale. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Claims in Ferndale and neighboring Pleasant Ridge tend to follow three patterns, and each one comes up short in its own place.
- Fire next door. After the January 2026 fire near Nine Mile and Pinecrest, the fire chief said the house would have to be demolished, and the houses on both sides were damaged too. When homes sit this close, heat and smoke reach the neighbors' siding, attics and ductwork, and the insurance company may write those homes up as a cleaning job. Smoke moves inside older walls, so the testing and the scope have to go past what you can see from the room.
- Burst pipes and overflows in pre-1940 houses. With 42 percent of Ferndale's housing built in 1939 or earlier, and Pleasant Ridge's historic district built mostly between 1910 and 1930, a supply line that splits in a hard freeze or an upstairs tub or toilet that runs over comes straight down through a plaster ceiling. Water that started in the house is sudden water, and so is water that comes up a floor drain because the home's own drain line broke: that is a fill-up that usually gets the full policy, not a back-up from an overloaded city sewer with its lower limit, and a plumber's written cause usually settles which one it was. These claims go short on the count, with plaster written as drywall and a bathroom priced in a handful of lines.
- Impact damage to apartment and commercial buildings. In February 2025 a car crossed the Nine Mile boulevard and ended up overturned inside an apartment building, leaving serious structural damage, and in April 2024 straight-line winds tore part of the roof off the Autumn House building on Nine Mile. On impact claims the insurance company often prices the visible opening and declines to open the walls and ceilings around it, where shifted framing and broken connections sit.
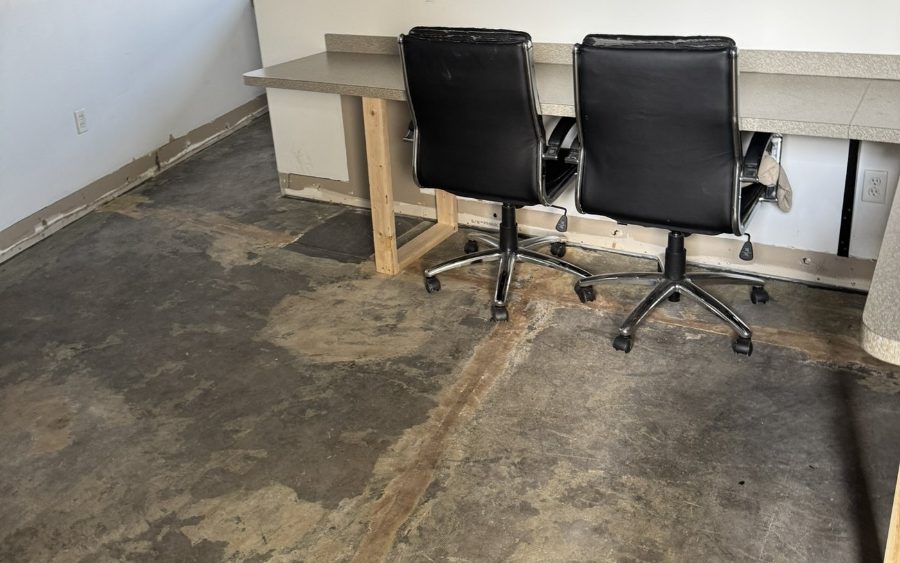
An offer of $11,630 on a commercial water loss that settled at $113,600.
Water through a Royal Oak office. The scope on the table stopped well short of the building. We itemized it, backed the materials with lab reports, and settled in three months.
Questions we get here.
A fire next door damaged my Ferndale home. Whose policy pays?
Usually your own. Your homeowners policy can cover smoke, heat and water damage to your house wherever the fire started, and your insurance company can pursue the neighbor's side afterward. Get the damage documented before any cleaning starts, keep the fire department's incident number, and have the policy read before you accept a wipe-down payment.
My house in Ferndale or Pleasant Ridge still has plaster walls. Does that change the claim?
It can change the number a great deal. Plaster and lath cost more to repair than drywall, and the cracking often runs well past the spot where the water or fire did its damage. Estimates tend to price it as drywall and stop at the stain. We record what the walls are actually made of and how far the damage runs, then price the repair to match.
How fast can someone get to a Ferndale property?
Quickly. Our office is on Woodward Avenue in Ferndale, so most addresses in the city and in Pleasant Ridge are a few minutes away. Call the number on this page and you will reach someone who can tell you what to photograph and keep before cleanup starts, and when an adjuster can meet you at the property.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.