Public adjusters in Midland, Michigan.
Midland has 423 documented mid-century modern buildings, from houses to churches and schools, and a median home value of $203,900. Custom designs, better finishes and full households of belongings are what an estimate written with builder-grade materials and a short contents list leaves out.
AdjustFair works only for the policyholder, from our Greater Flint office on Flushing Road, about an hour away by US-10 and I-75. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Three kinds of loss weigh heaviest on Midland homes, and each tends to get underpaid in its own way.
- Fire and smoke in larger homes. In March 2026 a fire that began in the basement of a two-story home on Rodd Street left fire and smoke damage through the house. In a bigger home, smoke rides the stairwell and the ductwork to every floor, and the contents, counted room by room, are often the largest part of the claim and the part most often undercounted.
- Trees through the roof. On May 31, 1999 a tornado crossed Midland's northeast side, snapping 40 to 60 foot trees on Woodpark Street and tearing the roof off the Holiday Inn on Wackerly Street, and a January 2024 snowstorm sent a tree through a Midland County home, nearly splitting it in half. On impact claims the insurance company often prices the roof and the visible ceiling and declines to open the walls, where broken rafters and shifted framing hide.
- Burst pipes and overflows. The January 2024 storm left more than 181,000 Consumers Energy customers without power, with Midland among the hardest hit counties, and a house without heat for days can freeze a line in an outside wall. In a two-story home a split pipe, or an upstairs tub, toilet or sink that runs over, can soak finished ceilings, floors and cabinetry below, and the claim is largely decided in the first week by the drying logs, moisture readings and photos.
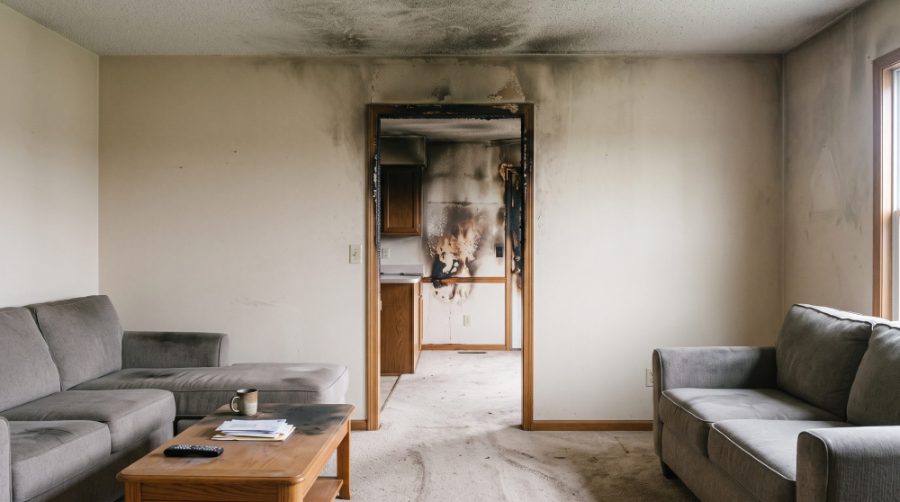
An offer of $84,559, and the appraisal that nearly doubled it.
A house fire in an older Mid-Michigan home. Documented with DocuSketch and resolved at appraisal, with interest for the time the claim took.
Questions we get here.
My Midland home is a custom or mid-century design. How do you price a repair on it?
By what is actually there. Low-slope roofs, custom millwork, wood paneling and large expanses of glass get swapped for stock materials in a typical estimate. We document the design and the materials, get pricing from contractors who build that way, and put the line items in front of the insurance company one by one.
The power was out for days in Midland and our pipes froze. Is that covered?
Often, but it depends on the policy. Many policies exclude freezing only when the owner failed to keep the heat on or shut off and drain the water, and a utility outage you could not control is a different set of facts. Write down when the power went out and came back, keep the plumber's report, and photograph everything before cleanup starts.
Is Midland too far for you to come out?
Not for a serious loss. Midland is about an hour from our Greater Flint office on Flushing Road, so we make the trip for major fire, water and structural claims. Call (810) 617-2222, describe the damage, and we will tell you plainly whether we can help and when an adjuster can be there.
Nearby
See every community we cover from our Greater Flint office on Flushing Road.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.