Public adjusters in Roseville, Michigan.
Roseville more than tripled in the 1950s, to over 50,000 residents, and nearly seven in ten of its homes predate 1970. On July 6, 2019 fast rain overwhelmed the sewers, filling basements on Blumfield Street and under City Hall. In houses this age, what sits in the basement decides much of a claim.
AdjustFair works only for the policyholder, from our Ferndale office, about 11 miles west of Roseville. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Three kinds of loss shape most serious Roseville claims, and each one is underpaid in a predictable place.
- Sewage and water in the basement. In the July 2019 storm parts of Roseville took two to four inches of rain, manholes lifted off their bases, and residents described a foot and a half to two feet of water in basements, mixed with sewage. Water pushed in from an overrun public system is a back-up, usually paid under an endorsement with its own limit, while water from the home's own broken line is a fill-up that started in the house and usually gets the full policy, and a plumber's written cause usually decides which. Either way sewage is category 3 water, so porous materials come out rather than being dried, and everything stored below grade needs a full list.
- Fire and smoke in apartments and houses. On March 14, 2025 a fire that started on the first floor of the Macomb Manor apartments on Masonic spread to the unit above, and every unit in the building had smoke damage. In December 2025 a fire on Brohl Street destroyed a family's home and everything in it, and they may be out for at least a year. Units away from the flames tend to be written as a light cleaning, and on a total loss the living expenses and the contents list become a large share of the claim.
- Industrial buildings. On April 22, 2025 a blast and fire at RCO Engineering's 20,000 square foot building on 12 Mile Road brought the roof down onto the interior, and the fire rekindled two days later. When a roof collapses, the first estimate is often written from what can be reached, while the walls, slab, electrical and equipment underneath go undocumented until the debris is cleared. Debris removal and the income lost while a line is down both need to be checked against the policy.
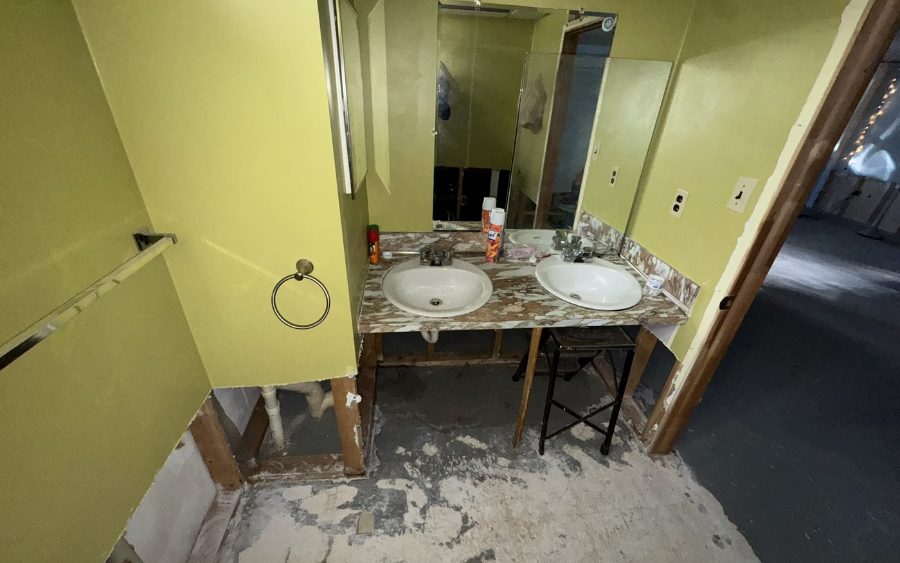
The contents were priced as cleanable. Appraisal called them a total loss.
Water backed up into a Sterling Heights home and stood across the lower floor. The first offer treated what it had touched as cleanable. Appraisal disagreed.
Questions we get here.
Everything stored in our Roseville basement was ruined. How do we prove what was there?
Start with photos and video of every item before it goes to the curb, which is what Roseville's mayor asked residents to do after the 2019 storm. Then build the list room by room: furniture, appliances, tools, clothing, holiday boxes, photo albums. Old phone pictures, receipts and bank records help fill the gaps. Sewage-soaked items can go once they are recorded, but nothing should leave uncounted.
A fire put our Roseville family out of the house. What does the policy pay while we are gone?
Most homeowners policies include additional living expense, sometimes called loss of use, which pays the extra cost of living elsewhere while the house is repaired or rebuilt: rent, extra mileage, laundry, meals above your normal grocery bill. After the Brohl Street fire the family expected to be out for at least a year. Keep every receipt from the first night, and check the policy's time and dollar limits early.
How soon can an adjuster get to Roseville?
Roseville is about 11 miles from our Ferndale office, and I-696, which runs along the edge of Ferndale, goes straight through the middle of the city. Call the number on this page and someone will explain what to do first, what to photograph before cleanup, and when an adjuster can see the house, the apartment or the building with you.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.