Public adjusters in St. Clair Shores, Michigan.
St. Clair Shores was the fastest-growing Detroit suburb of the 1950s, but its shoreline is older: Eagle Pointe was laid out along Lake St. Clair in 1916. An older lakefront house, or a post-war home with original framing and finishes, costs more to put back after a fire or a burst pipe than the $211,000 median value suggests.
AdjustFair works only for the policyholder, from our Ferndale office, about 12 miles west along I-696. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where St. Clair Shores claims get underpaid.
Three kinds of serious loss fit St. Clair Shores' housing, and each one has a familiar way of coming in short.
- Fire, smoke and water in post-war houses. Most of the city's subdivisions went up after World War II, and about six in ten homes predate 1960. Smoke settles into attics, ductwork and wall cavities that an estimate treats as untouched, and a kitchen fire gets written as a cabinet swap instead of the tear-out and rebuild it usually is. Water does its own hidden damage in these houses when an upstairs tub, toilet or sink overflows through the ceiling below, and water that comes up a basement floor drain because the home's own aging sewer line broke is a fill-up (some call it an overflow) that started in the house and usually gets the full policy, not a back-up from an overrun city system held to a sublimit; the plumber's written cause usually settles which it was.
- Waterfront homes and condos. In April 2013 a fire at the St. Clair by the Lake condominiums off Jefferson started near a fireplace, ran into the attic and dropped the roof and both floors into the basement, destroying two waterfront units and damaging two more. Larger and custom lakefront homes tend to get priced with builder-grade materials, and the contents in them are routinely undercounted.
- Trees and wind through the structure. On May 4, 2026 a large tree came down on a house near 13 Mile and Jefferson and left it with severe structural damage. When a tree or a storm opens the roof, the insurance company often prices the visible break and declines to open walls and ceilings, where cracked rafters, shifted framing and wet insulation usually turn up.
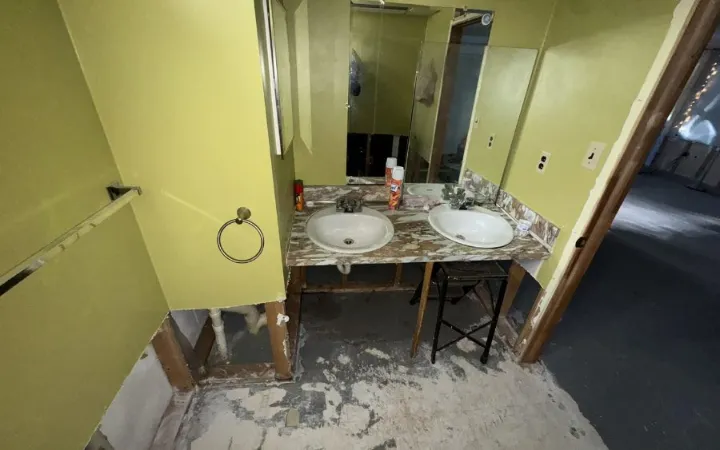
The contents were priced as cleanable. Appraisal called them a total loss.
Water backed up into a Sterling Heights home and stood across the lower floor. The first offer treated what it had touched as cleanable. Appraisal disagreed.
Questions we get in St. Clair Shores.
A pipe let go or a tub overflowed in the condo above mine in St. Clair Shores. Whose policy pays?
Often more than one. The association's master policy may cover the building itself, your own unit owner's policy can cover your interior finishes, improvements and belongings, and the split depends on the bylaws and the policies. Get the plumber's written cause, photograph every ceiling and wall before drying starts, and keep the moisture readings.
A tree or winter storm opened my roof. What should the claim include?
More than the roof. Weight from a tree, heavy snow or ice can crack rafters and push framing out of line well away from the hole, and rain that gets in soaks insulation and ceilings below. Ask that the attic and affected walls be opened and documented before the estimate is settled, and keep the tree service invoice.
How long does it take to reach St. Clair Shores from your office?
Our Ferndale office is about 12 miles west, a straight run east on I-696, so the Nautical Mile and the neighborhoods along Jefferson are well within reach. Call the number on this page and you will get someone who can tell you what happens next and when an adjuster can come out to the property.
Nearby
See every city we cover from our Metro Detroit office in Ferndale.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.