Public adjusters in Flint, Michigan.
Seven in ten Flint homes were built before 1960, including about 950 Civic Park houses General Motors put up in 1919 and 1920. On a replacement cost policy, a fire or a split pipe is priced by what it takes to rebuild plaster, old framing and original plumbing, not by Flint's $63,000 median home value.
AdjustFair works only for the policyholder, from our office on Flushing Road on Flint's west side. We read the policy, document the full loss, price the repair the way a contractor would have to build it, and put that number in front of the insurance company with the proof behind it.
Where claims here get underpaid.
Three kinds of loss matter most for Flint homes, and each has its own way of coming in short.
- Fire and smoke from the house next door. A 2022 Land Bank report found about one in four Flint homes vacant, blighted or both, arsons rose 41% in 2023, and the fire chief says most fires are started by squatters in vacant houses. When one spreads, the estimate on the occupied home next door often stops at the scorched siding, while smoke has moved through old framing and ductwork into every room.
- Blast and impact damage around an explosion. In November 2021 a gas explosion on Hogarth Avenue killed two people and damaged about 30 nearby homes. Houses that never caught fire still take cracked plaster, broken windows, racked door frames and shifted framing, and the insurance company often pays for the glass while refusing to open the walls where the real damage sits.
- Frozen and burst pipes. Flint spent 36 hours below zero in January 2019, and a cold snap in February 2026 broke 20 city water mains in 24 hours. In a house from the 1920s or 1950s, one split line in an outside wall, or an upstairs tub, toilet or sink that overflowed and ran through the ceiling below, can soak plaster on two floors, and the claim is largely settled in the first week by the moisture readings, drying logs and photos. In houses that old, water that comes up through a basement floor drain because the home's own drain or sewer line collapsed or broke is a fill-up (some call it an overflow), meaning it started in the house and usually gets the full weight of the policy, not a back-up, where an overwhelmed city system pushes water in and a lower sublimit usually applies; where the water started decides it, and the plumber's written cause usually settles it.
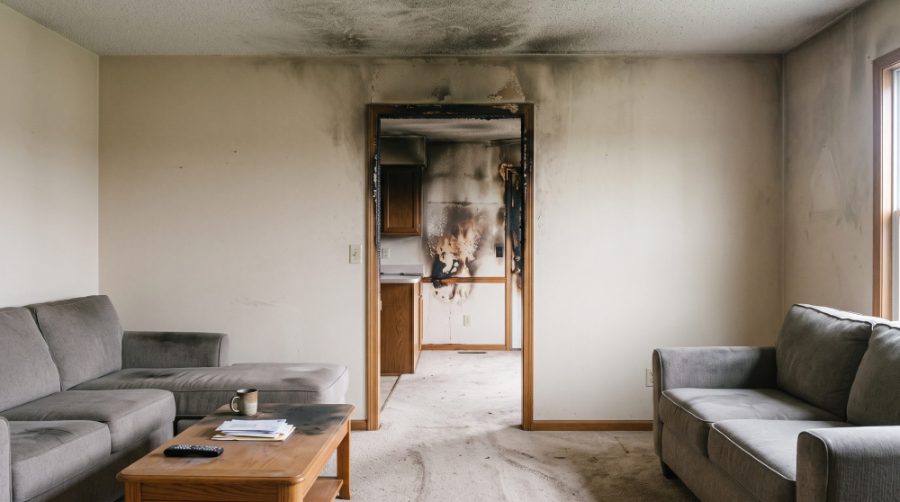
An offer of $84,559, and the appraisal that nearly doubled it.
A house fire in an older Mid-Michigan home. Documented with DocuSketch and resolved at appraisal, with interest for the time the claim took.
Questions we get here.
The vacant house next to mine in Flint burned. What should my claim include?
More than the melted siding. Radiant heat can crack windows and blister paint well past the scorch marks, and smoke gets into attics, wall cavities and ductwork in an older house. Clothing, bedding and furniture usually need cleaning or replacement too. Have the whole house inspected and the smoke odor documented room by room before you accept an estimate.
A blast or a car hit my Flint house but nothing collapsed. Is the damage really that small?
Often not. A sudden impact can crack plaster, break joints in old plumbing and shift framing that looks fine from the outside, and those problems show up inside walls and ceilings. Ask for the affected walls to be opened and documented, keep the police or fire report, and do not sign off on a payment for the visible damage alone.
How fast can an adjuster reach a Flint home?
Our Greater Flint office is on Flushing Road, a few miles west of downtown, so a Flint address is a short drive for us. Call (810) 617-2222 and you will reach someone who can walk you through the next steps and set a time for an adjuster to see the property.
Nearby
See every community we cover from our Greater Flint office on Flushing Road.
Let's find out where |your claim stands.
Tell us what happened and we'll tell you honestly what your policy covers and what we would do next. It costs nothing to ask.